

Accountant by trade, investor by choice. UK tax, markets and options, with the workings shown. NFA Education found here - https://xitter.twitterapi.xyz/t.co/CLBRhgTNC9.
Brentwood, Essex
Joined February 2026
- Tweets3.8K
- Following909
- Followers989
- Likes6.3K






Pinned Tweet
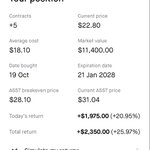
Big shift yesterday, I have liquidated ALL my passive ETFs in my S&S ISA and moved the balance to $HOOD
A beautifully boring 8% equity beta is not going to cut it for me right now, with changes in my personal life meaning I need to target higher growth.
The strategy in $HOOD is a premium funded convexity barbell and I will be selling monthly deep out of the money cash secured puts on companies I have valued and want to own.
The harvested premium funds long dated calls for uncapped tail upside, or aggregates into future CSP's. If I am assigned, I hold the stock and write covered calls above my cost basis.
The capital cycle is strict and I must be disciplined:
50% of proceeds swept back to the ISA
24% into digital credit yielding 13% as a holding pen for CGT
26% recycled into options to snowball the position
To be clear, I do NOT recommend anyone do this. My SIPP is and always will be my main portfolio, driven by heavy salary sacrifice. This is a highly specific, high-risk satellite strategy for my current situation.
3
12
1,219
MSCI just forced passive ETFs to dump billions of $MSTR because it failed their boomer test.
ETF investors just got rugged out of the best performing asset of the decade and I still believe the digital asset treasury model is the future of finance.
5
496
The Bank of England said today that unemployment among 16 to 24 year olds is more than three times the rate for everyone aged 16 and over.
In the three months to August it was 15.6%, against 4.7%.
I think we've been making those first jobs more expensive to offer.
From April 2027 most unused pension pots count for Inheritance Tax. If the saver dies at 75 or over, Income Tax still hits the rest.
With the nil-rate bands used, £100,000 left to a 40% taxpayer becomes £36,000.
I'm against Inheritance Tax anyway. Taxing a pot twice is worse.
71
The CGT allowance was £12,300 in 2022/23, now £3,000.
A £10,000 share gain outside an ISA is £1,680 at the higher rate, against nil then.
I think the cut did far more than the move to 24%.
I also think long-term holds should be adjusted for inflation.
uktaxdrag.co.uk/uk-capital-g…
1
4
357
I think Plan 2 is a badly designed loan.
You can make every repayment and still owe more at the end of the year.
On £40,000 that's about £955 a year, 9% above £29,385. If you owe £50,000, the interest is about £2,730.
I think the Budget should have reviewed it.
2
8
988
$NVDA is down nearly 6% today, after 4% yesterday. From last month's high that's almost 30%.
The leather jacket I can price in but an alleged affair with a Chinese spy is a bit harder to model.
Is this worth a buy right now, or do you wait until after earnings?
1
3
390
Employer NI on a £25,000 salary is £3,000 a year, up from £2,194 before April 2025. That's 12% of pay, from 8.8%.
On £100,000 it went from 12.5% to 14.25%.
The Bank of England says young people are bearing the hiring freeze. I think the £5,000 threshold cut hit the wrong jobs.
Anyone in England earning £20,000 to £50,000 would pay £1,486 less Income Tax a year with a £20,000 Personal Allowance.
The petition for it passed 10,000 signatures today, so the Government now has to respond.
I'd back that over another targeted relief. petition.parliament.uk/petit…

Someone on £40,000 in England pays £760 more Income Tax this year than they would if thresholds had kept pace with prices since 2020.
The allowance stays frozen until 2031, and the Bank of England sees inflation near 5% by mid-2027. uktaxdrag.co.uk/uk-fiscal-dr…
2
3
218
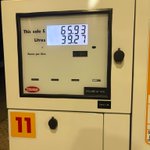
£65.93 to fill up the little 1.1L Ford and I still had 87 miles left in the tank.
I'd honestly thought prices would have come down more by now.
I worked out the tax on it:
£20.79 was fuel duty and £10.99 was VAT, which is charged on top of the duty.
Scandalous

6
6
1,297
Dan - Accrue Returns retweeted
Digital credit took four centuries to make possible. From the Dutch East India Company to Bitcoin, this is the story of the ten foundations that brought us here. $STRC

What interests me is the capital structure, a bitcoin treasury financed through securities with different claims on the issuer.
$STRC separates income exposure from common equity upside and that distinction matters more to me than the label "digital credit".
Incredibly smart!
Digital credit took four centuries to make possible. From the Dutch East India Company to Bitcoin, this is the story of the ten foundations that brought us here. $STRC
2
199
I think the proposed Pension Tax Allowance is an unfair patch on a frozen £12,570 Personal Allowance.
From April 2027, a pensioner on £13,036.40 would pay no Income Tax. A younger worker in England on the same would pay £93.28.
I'd rather the allowance rose for everyone.
4
9
874
Dan - Accrue Returns retweeted

Calling all options degenerates 🚨⚠️
LEAPS n' Greeks, spreads... and the occasional financial catastrophe.
Whether you're just curious to learn more, you dabble in a few cheeky calls, or you dream about iron condors in your sleep... you are all welcome.
I've noticed, particularly in the UK, options are under-utilised and wildly misunderstood. They can be daunting to get into, and as far as I am aware, there is no dedicated community for people to bounce ideas off each other for options plays and strategies.
Well today that changes.
Welcome to The IV League 🎓
Let me know if you want in to the group 🫡🐧
Brilliant idea mate, options in the UK feel so far behind and too many people get put off before they've even learned the basics.
A community where people can share ideas and learn from each other is exactly what's been missing.
Proud to be part of The IV League 🎓

Calling all options degenerates 🚨⚠️
LEAPS n' Greeks, spreads... and the occasional financial catastrophe.
Whether you're just curious to learn more, you dabble in a few cheeky calls, or you dream about iron condors in your sleep... you are all welcome.
I've noticed, particularly in the UK, options are under-utilised and wildly misunderstood. They can be daunting to get into, and as far as I am aware, there is no dedicated community for people to bounce ideas off each other for options plays and strategies.
Well today that changes.
Welcome to The IV League 🎓
Let me know if you want in to the group 🫡🐧
1
8
374

I think UK investors need a much better understanding of options. They're a big part of how I invest, from premium plays to LEAPS, and I'd love to see more people take the time to learn how they work.
Explore the guides at UK Tax Drag: uktaxdrag.co.uk/options-trad…
I think the High Income Child Benefit Charge is unfair because it tests each parent's income, not the household's.
A family with one earner on £80,000 of adjusted net income repays all of its Child Benefit. A couple on £60,000 each, £120,000 between them, repays none of it.
2
7
730