

Tokenized securities and portable identity.
NYC
Joined April 2024
- Tweets2.2K
- Following1K
- Followers6.3K
- Likes3.7K


Something tells me today seems like not the best day to bullpost zkKYC and verified identity for tokenized securities issuance that can reach outside of the existing intermediary system.
Identity is the final piece issuers and TSVs need for the @SECGov's Innovation Exemption to take tokenized securities to billions of investors worldwide.
Post by @EulerLagrange
opacitylabs.com/newsroom/the…


Opacity Labs retweeted

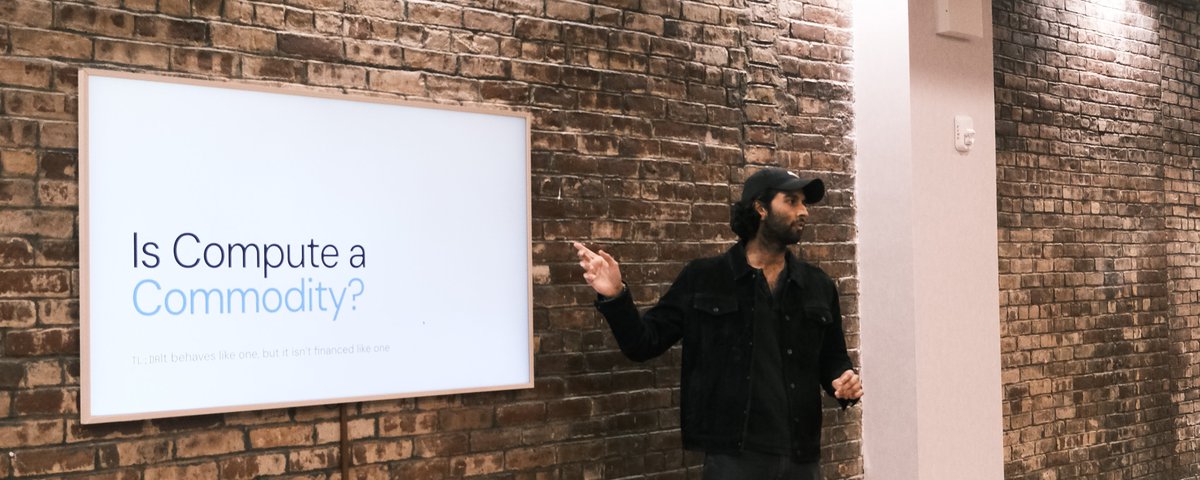
1 week late, but here are some expanded thoughts from my presentation on "Is Compute a Commodity" from last week.
Read on to find out the 5 reasons why compute is a commodity, and the 3 reasons it is not!


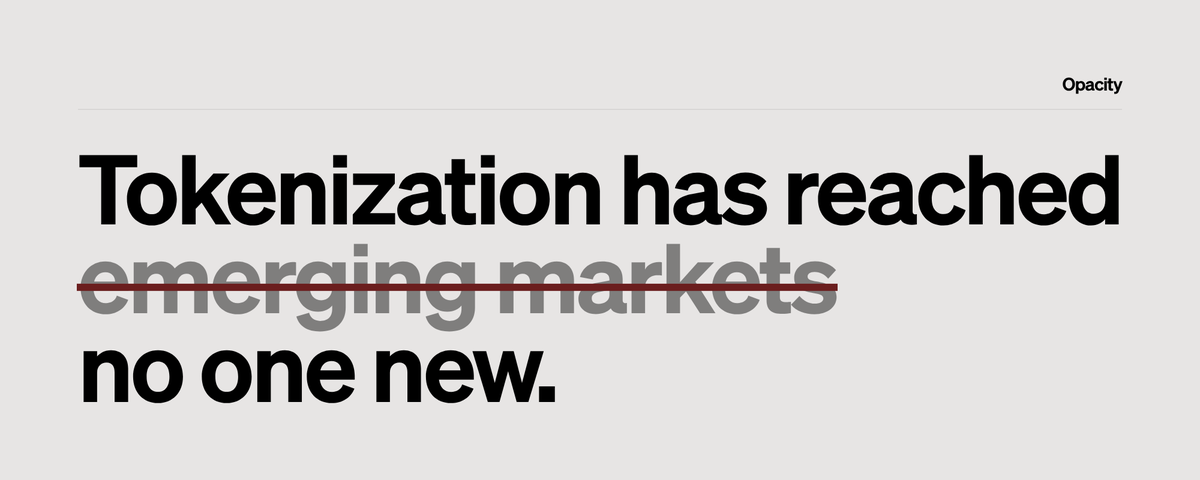


Tokenization is useful because programmable assets can travel outside of trad venues, yet within the rules set by the issuer.
Opacity is deterministic, neutral tech that allows access to financial assets according to the rules set by the issuers within their legal obligations.
What you're describing is internal transfers between accounts at one brokerage, that's been possible since brokerages existed. The blockchain here is doing nothing the broker's own account database doesn't already do.
Tokenized receipts are fine, wBTC and USDC are good examples. They work because it allows any AMM, Vault, Venue, CEX etc to work with each other without bespoke coordination, they just adopt the same software standards.
What people want from tokenization isn't no rules, it's no gatekeeper. Define the rule(s) in a smart contract and let anyone show up and prove they satisfy the rules. What Brett advocates for is the opposite, the rule is "the wallet must have a brokerage account with Securitize to transact."
Extrapolate the model and the end state is one brokerage everyone has to onboard with, because that's the only place the tokens can go.
I don't understand how anyone calls this innovation, it's rewinding the clock of American capital markets.
Opacity Labs retweeted

this panel caused the timeline to fork

-@eulerlagrange: zkTLS is increasing the brand value of zk… so shut the fuck up. 🎤💧
@SuccinctLabs hacker house

Until the input carries provenance of its source, verifiable inference use cases will be limited. Verifiable data comes first.
The bottleneck verifiable AI inference will hit:
A proof of inference only shows that the model ran correctly. The user supplies the input, so a forged input still yields a valid proof. Verifying the input is authentic is the bottleneck.
@AnthropicAI released FlashProve yesterday: a zkSNARK that an output came from a committed set of model weights. The user still checks only that their provider ran the right model. The moment the proof is shown to a third party as evidence, it is only as good as the input, and the proof says nothing about where the input came from.
Verifiable compute moves the trust from the party running the model to the party supplying the data.
That is why these proofs worked on blockchains first. A rollup's inputs are posted to the L1, so the proof covers data anyone can check. Off chain, there is a chronic shortage of verifiable data. A bank balance, a payroll record, a cap table or a lab result sits on a server that shows it to you over an encrypted connection. Once it leaves that server, it becomes a screenshot or a PDF.
Until the input carries provenance of its source, verifiable inference use cases will be limited. Verifiable data comes first. Verifiable compute is what you do with it.
@OpacityLabs

Opacity Labs retweeted
Tokenization has yet to solve a problem for issuers. Issuers will adopt tokenization because it gives them a direct relationship with their shareholders.
Market structure for the past 50 years denied issuers direct shareholder relationships, because settlement scaled much better when firms deposited with a central depository and settled trades with each other on the depository’s ledger.
Most attempts at tokenization are trying to pad the margins of the intermediaries. It’s no wonder issuers are opting out of tokenization intermediary relationships like OKX.
The promise of tokenization is simple: settle trades directly on the issuer’s register without recreating the late 60s paperwork crisis.
The main innovation we need is a better identity verification that multiple firms can rely on. Follow @OpacityLabs to learn more.
I’ll include specific examples issuers have in the current market structure below 👇

50 objections. Opting out just moves tokenization to markets that never asked for consent.
xitter.twitterapi.xyz/EleanorTerrett/status/…
Attribute-based Credentials attest to facts such as citizenship, accredited investor status, absence from sanctions lists, without revealing the underlying data.
opacitylabs.com/reusable-cre…


6
463
Opacity Labs retweeted
I want to drill into @drwconvexity’s point of "the benefit of being onchain is no KYC" because it mixes two things.
The KYC (really BSA) obligations are the main reason liquidity in traditional markets is fragmented. What people actually want from "no KYC" is the absence of a gatekeeper, not anonymity.
With better digital identity you can get rid of the gatekeeper without getting rid of the rule. Write the eligibility rules into smart contracts, and let the person prove they satisfy them.
This is more possible than people think. At @OpacityLabs we built it. It works as a one-time KYC that is stronger, and it makes the ongoing BSA work cheaper (happy to provide more detail).
So the trade is not "KYC or liquidity."
You can have one shared pool of liquidity across market types and give regulators what they want. That is what @0xmev’s version of Hyperliquid should look like onshore.
Our tools let asset managers, fintechs and TSVs verify and onboard investors with reusable, attribute-based credentials. The implications are tremendous.
Credentials are fundamental to upgraded financial rails.

The pitch CEOs keep hearing for tokenized stocks is 24/7 trading. That is an exchange benefit. Venues earn fees on volume. Issuers do not.
Companies raise capital by selling shares to people who believe in the business. They want more holders who understand what they are buying.
That means demand from new buyers. There are many of them in emerging markets who want U.S. equities and have not been able to get onto traditional venues with access to the full range of U.S. stocks. Tokenized stocks can reach those people.
Issuers still need to know who is holding. They have responsibilities to existing shareholders and to regulators. That is a fair critique. There is overblown panic in this ad, but the resistance makes sense. We need to meet in the middle so we get the benefits of tokenization without scaring off the biggest new potential users.


