

Most housing headlines are wrong. I break down what’s actually happening in real time. $3.5B+ sold | 8,500+ units since 2020 60k+ subs on Substack Newsletter
Jacksonville, FL
Joined August 2015
- Tweets22K
- Following297
- Followers21.9K
- Likes3.6K
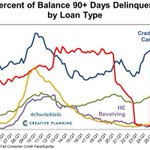


5.7% of auto loans are delinquent 90+ days... the highest on record
10.9% of student loans are delinquent 90+ days
12.9% of credit card balance are delinquent 90% days...
How does this end?

Before buying a home...
Ask yourself one question:
Who buys this from me in 10 years?
Population growth is slowing.
Migration is slowing.
Affordability is worsening.
Future demand matters more than past appreciation.
A housing correction happens in this order:
Payments become unaffordable
Buyers disappear
Transactions collapse
Inventory accumulates
Sellers cut prices
The crash doesn’t begin with panic.
It begins with an empty open house.
Sellers are waiting for a buyer who no longer exists.
That buyer had a 3% mortgage, cheap insurance, and stimulus-era savings.
Today’s buyer has a 7.2% rate, record prices, and rising living costs.
Yesterday’s price.
Today’s payment.
That math doesn’t work.
Mortgage demand has crashed. It's only going to get worse from here folks.
I keep talking to big real estate investor friends and they keep saying "it's already over"... but we are really in the early innings..
This is end of a cycle an we are transitioning into a new one.
The sooner you look at the big picture, the better.

The math broke
Institutional investors are net sellers

Imploded
That's the best way to describe the third-party homebuilder pipeline at Invitation Homes—a giant SFR landlord
Despite the fact that more giant homebuilders are offering discounts of +20% below market/list to institutions right now, Invitation Homes is still largely passing up on those deals
3 big reasons...
1, Yields on SFR acquisitions are less favorable in the current environment (that's been the case since mid-2022)
2. Invitation Homes' stock is trading well below what Invitation Homes says their aggregate home portfolio is worth, so they'd rather buy back stock
3. Invitation Homes recently bought ResiBuilt (an in-house BTR developer). So they're brining some of the building in-house (although, ResiBuilt will build for other funds/operators as well)
Chart via @ResiClub_HQ

Home Prices Fell. Buying a House Got More Expensive. What?!
youtu.be/sCELpTI9DR0
2
1
906
People don't realize how much economic activity disappears when nobody buys houses.
No sale.
No mortgage.
No title closing.
No moving company.
Less spending on furniture, appliances, renovations, and repairs.
A housing slowdown doesn't stay inside the housing market.
It spreads through the economy.
And transaction volume is where the damage shows up first.
Builders are sitting on 113,000 finished homes with no buyer.
In Feb 2022 it was 31,000.
Levels we haven't seen since 2009.
That's not a housing shortage.
That's inventory.


Inflation continues to be so destructive to the middle class.
The government doesn't care.
They recklessly spend your money.
They take more than half your money in taxes, and are still wildly in debt.
How much longer are we going to accept this?

Zillow counted 242 US cities this year where a starter home is worth $1 million or more.
Before the pandemic it was 80.
Florida has 11 of them.
The typical starter home nationally is still about $199,000.
So the national number tells you almost nothing about your town.


Apartment building loans keep going bad.
8.09% of multifamily CMBS loans were delinquent in October, per Trepp.
Two years ago it was 3.24%.
Office is even worse at 12.33%.
Apartments were supposed to be the safe one.

BREAKING: The delinquency rate on multifamily Commercial Mortgage-Backed Securities (CMBS) rose +5 basis points in October, to 8.1%, its highest since 2016.
This figure has more than quadrupled since 2024.
Furthermore, the delinquency rate on CMBS for offices jumped +17 basis points last month, to 12.3%, matching the all-time high set in January 2026.
To put this into perspective, this percentage peaked at ~10.8% in 2012, following the 2008 Financial Crisis.
The commercial real estate crisis is still worsening.

The young are getting poorer and the old are getting richer.
This is actually an important housing signal.

Amendment 3 is already hitting St. Johns County.
The county put about $100 million in projects on hold. That includes a new fire station.
By year two it could lose about 32% of its property tax revenue.
Homeowners get a big tax break. Fast growing counties still need roads, fire and police.
If you're buying in St. Johns, watch the December budget meeting.

Amendment 3: Pain Deferred.
Across Florida, local governments are reaching for the easiest cuts first.
🏗️ Manatee County: Proposed community center on the chopping block.
📚 Sarasota County: $11 million Longboat Key library project at risk.
🚒 St. Johns County: $100 million in capital projects on hold, including a planned fire station.
🚧 Jupiter: More than $20 million in potential delays, including road improvements, community center renovations and five parks.
But here’s the problem: You can only cancel a project once.
Amendment 3 creates recurring revenue losses approaching $12 BILLION annually statewide. Canceling construction projects may provide one-time relief, but it doesn’t solve a recurring operating deficit.
Next year, the revenue is still gone. The year after, it’s still gone. Meanwhile, salaries, insurance, equipment and maintenance keep getting more expensive.
You can cancel a library once. Delay a road project once. Shelve a fire station once.
Eventually, you run out of projects to cancel and start cutting the services people depend on, including police, fire EMS, and other core services. I get it many are just looking for a little extra time before the real cuts kick in.
Just understand the easy cuts come first and that’s not solving the problem. That’s pain deferred.
