

Researcher and Visual Educator : DeFi • Tokenization • NeoFinance • AI | Top Research in Highlights (Formerly known as @Mars_DeFi)
Blockchain
Joined December 2014
- Tweets27.1K
- Following3.6K
- Followers28K
- Likes41.3K





If you can lock in a borrowing rate for 90 days, you can plan a 90-day strategy around it.
That’s what fixed rates bring to DeFi and they’re showing up everywhere from lending order books to principal tokens and interest-rate swaps.
So what are you actually locking in with each one?
Here’s how the landscape works.
—
● Fixed-term lending and borrowing
Variable-rate markets like @aave , @Compound , @Morpho Blue and @sparkfinance made it easy to borrow from shared liquidity pools. In those markets, borrowing costs can rise as more of the available liquidity gets borrowed.
Fixed-term credit markets let borrowers and lenders agree on a rate upfront for a defined term. The main difference is how each market sets that rate.
• @term_labs uses sealed-bid auctions. Bids and offers clear at one rate for that auction’s term.
• @Loopscale uses a credit order book to match lenders and borrowers on fixed-rate, fixed-term loans.
• @jupiter_earn Offerbook lets lenders post offers for short-term, collateral-backed loans. If a borrower fails to repay on time, the lender can claim the collateral.
• @ExactlyProtocol runs separate fixed-rate pools for different maturity dates alongside its variable-rate pools.
• @Morpho Midnight uses offers to trade units that settle on a specific date. The price of those units determines the rate for the remaining term.
• @TermMaxFi uses discounted Fixed Rate Tokens, while Secured Finance uses an onchain order book for zero-coupon instruments. In both designs, the gap between today’s price and the amount due at maturity determines the implied rate.
• @Fira_Lend uses a maturity-based AMM and discounted Bond Tokens. Lenders can buy the tokens to lock in a return to maturity. Borrowers can post collateral, borrow the tokens, and sell them for the underlying asset to lock in their financing cost.
@NotionalFinance was an early example of this model. Its fCash represented a claim or obligation due on a future date. The original V3 markets are winding down, so fCash is best understood as part of the history of fixed-rate DeFi.
—
● Fixed yield through principal tokens
If your goal is to earn a predictable return through a specific date, @pendle_fi and @spectra_finance offer another route. They split a yield-bearing position into a Principal Token (PT) and a Yield Token (YT).
Say you buy a PT for 95 units and it redeems for 100 units at maturity. The five-unit difference is your return before fees, assuming redemption goes as expected. If you sell early, the market price determines what you get back.
The practical question is whether the maturity fits when you’ll need the capital. A good quoted APY can look very different if you have to exit early.
—
● Borrower-set rates and borrowing rights
Some protocols give borrowers more control over how they pay for credit.
• @LiquityProtocol V2 lets you choose and adjust the rate on your BOLD debt. That rate also affects your position’s redemption priority.
• @WildcatFi lets borrowers set the terms of custom credit markets. Its fixed-term configuration can block withdrawals and base APR reductions for a set period, after which the market becomes open-term.
• @InverseFinance’s FiRM lets borrowers buy DOLA Borrowing Rights upfront. The price paid for those rights determines the financing cost for the period they cover.
• @flexmeow uses a collateral-backed borrowing model with lender vaults.
Worth notingis that @eulerfinance fits into the picture at the infrastructure level. Its Vault Kit lets curators configure lending markets and choose their interest-rate models, so the rate terms depend on the specific vault.
—
● Hedging a floating rate
@ipor_io approaches the problem through interest-rate swaps. A borrower can pay a fixed rate and receive a floating rate on the swap, using that floating payment to offset some of the exposure on an existing loan.
How well the hedge works depends on how closely the swap’s reference rate tracks what the borrower actually pays.
—
For me, the useful comparison starts with what I’m trying to lock in.
If I’m running a carry trade, I want to know my borrowing cost until the trade ends. If I’m lending, I want to know when I get my capital back and what happens if the borrower misses repayment. If I’m buying a PT, I want to know what it redeems for and what I can sell it for if I need to exit early.
The rate offered is always just a number but the maturity, repayment terms, and exit liquidity tell you whether it fits the position.

Deposits are closed and now comes the part I’ve been looking forward to.
@Infinit_Labs wrapped up APEX Multi-Strategy Phase 2 with over $4M in deposits. Next up, the vault puts that capital to work trading perps on Hyperliquid.
What excites me about APEX is that it can look for trades across crypto, commodities, and equity indices. When one market goes quiet, the strategy can look for opportunities elsewhere.
I’m looking forward to that first performance update. I want to see where APEX finds its best trades, how it adapts when the market shifts, and what that looks like over a full term.
I’m rooting for a strong Phase 2. If APEX can find good trades across different markets, we’ll have a real example of what active onchain asset management can do.
🤝 Paid partnership

3
13
581
A DeFi carry trade can go from a 4% gross spread to a 2% loss even when the strategy’s yield stays the same. All it takes is a jump in borrowing costs.
@kamino’s $85M+ in fixed-rate loan originations points to growing demand for a way to lock in those costs.
Two models are emerging to meet that demand. @iris_credit uses solvers to turn existing lending liquidity into fixed-rate loans. @avon_xyz uses an order book to match borrowers and lenders directly.
—
● Why DeFi Needs Fixed-Rate Borrowing
Most DeFi lending markets, including @aave use variable rates tied to how much of the available liquidity is borrowed. As utilization rises, so does the cost of borrowing. That makes longer-duration strategies harder to price upfront.
Take a carry trade earning 9%. At a 5% borrowing rate, the gross spread is +4 percentage points. If the borrowing rate rises to 11%, the spread falls to −2 percentage points.
A fixed-rate loan locks the financing cost for a defined term. The strategy’s yield can still move, but the borrower knows what the debt will cost.
The question is how to deliver that fixed rate. IRIS and Avon differ in where they source capital, how they discover rates, and who takes the interest-rate risk.
—
● @iris_credit + @sparkfinance (Fixed Rates Through Solvers)
@iris_credit adds fixed-rate borrowing to @sparkfinance by sourcing capital from SparkLend’s existing pools.
1. The borrower sets the terms
A borrower puts up $ETH as collateral and requests 100,000 $USDC for 180 days at a maximum fixed APY of 7%.
2. Solvers compete to fill the loan
Through a request for quote (RFQ), Solver A offers 6.2%, Solver B offers 6.5%, and Solver C offers 6.8%. Each quote is backed by a bond, and the borrower can accept any offer within the 7% cap.
3. The loan settles on SparkLend
The borrower receives the USDC in a single transaction and pays the agreed fixed rate. The solver pays SparkLend’s floating rate and takes the difference.
At a 7% fixed rate, the solver earns a 2-percentage-point spread when SparkLend charges 5%. If the floating rate rises to 12%, the solver faces a 5-percentage-point loss, with its bond backing settlement.
This gives IRIS access to SparkLend’s existing liquidity, with $4.7B in TVL and loan terms ranging from one day to two years.
—
● @avon_xyz + @aave (Fixed Rates Through an Order Book )
@avon_xyz uses an onchain central limit order book (CLOB). Borrowers submit the amount they need and the maximum rate they’ll pay. Lenders specify how much capital they’ll offer and the minimum rate they’ll accept. The order book matches compatible orders, and rates emerge from that competition.
Each market can set its own interest-rate curve, loan-to-value limits, liquidation rules and other risk parameters. An aggregated order book lets borrowers access the best available terms across markets while each market maintains its own risk settings.
@aave acquired Avon’s technology and team to bring order-book-based credit into its ecosystem. Combined with Aave V4’s hub-and-spoke architecture, it could support specialized markets for tokenized Treasuries, private credit and tokenized equities, each with separate risk parameters.
—
● Who Takes the Risk When Borrowers Lock Their Rate?
In variable-rate markets, borrowers absorb changes in financing costs, while lenders generally have more flexibility to withdraw when liquidity is available.
Fixed-rate credit shifts that exposure. In @iris_credit , solvers absorb the difference between fixed and floating rates. In fixed-term lending markets, lenders commit capital for a defined period and take on duration risk.
For vault curators, APY and collateral quality are only part of the decision. They also have to assess capital efficiency, maturity exposure, secondary-market liquidity, early exit options, and how rates are priced and losses allocated.
Managing duration becomes as important as managing collateral risk.
—
● @kamino Shows Where Demand Is Emerging
@kamino has originated $85M+ in fixed-rate loans on 30-day terms, with $35M+ renewed through Auto Rollover, which renews loans when capital is available.
Its RWA markets show where borrowers are using that financing.
• AUTO : ~$67M in originations at 5.30–6.25%
• OnRe : ~$17.8M at 7–8%
• Huma : ~$1M at 6.25%
The renewals point to demand for financing that extends beyond a single 30-day term. Borrowers are using fixed-rate loans to finance positions backed by tokenized real-world assets and rolling those loans forward when liquidity is available.
—
● The Fixed-Rate Credit Landscape Is Expanding
Beyond IRIS’s solver model and Avon’s order book, several protocols are exploring fixed-rate and fixed-term credit.
• @Morpho’s Midnight has $167M in cited TVL.
• @flexmeow is a fixed-rate credit initiative under @yearnfi.
• @lista_dao’s activity is primarily tied to slisBNB looping.
• @term_labs , @TermMaxFi and @Loopscale offer fixed-term credit markets.
• @LiquityProtocol V2 lets borrowers select their interest rate.
Liquidity remains thin across most markets, limiting how much borrowers can raise and how competitive rates can get.
—
● Why Predictable Financing Matters for Institutions
Institutions, fintechs and RWA issuers need to know what financing will cost over the life of a position so they can price loans and estimate returns.
• Fintechs can lock in borrowing costs when financing consumer loans.
• Tokenized Treasury holders can borrow USDC while keeping their assets.
• Private-credit funds can borrow against yield-generating collateral and estimate the spread they’ll retain after financing costs.
Variable-rate markets gave DeFi deep pools of liquidity. Fixed rates, defined maturities and competitive pricing could make that liquidity usable for businesses and institutions that need to plan around their cost of capital.
The next phase of DeFi lending may be measured by how much credit borrowers can reliably access on terms that fit their businesses.

Marspective retweeted
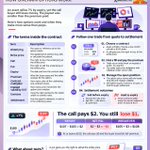
You buy a call expecting the asset to rise. It rallies 7% by expiry, and you still lose money.
Sounds strange, right? The call paid out, but the payout was smaller than what you paid for it.
If you’re new to options, here’s Options 101. I’ll break down what you’re buying, how the trade works from start to finish, and when options make more sense than perps.
—
● Options 101: What are you actually buying?
An option gives you the right to buy or sell an asset at an agreed price. You can use that right if it benefits you or let it expire. The seller gets paid upfront for taking on the other side of that agreement.
Here are the terms you’ll see on an options platform.
• Underlying : The asset or reference price the option tracks.
• Call : The right to buy at the agreed price. A call pays at expiry if the asset settles above that price.
• Put : The right to sell at the agreed price. A put pays at expiry if the asset settles below that price.
• Strike : The agreed price. It determines where the option starts to pay at expiry.
• Expiry : The date and time the contract ends. The contract rules determine when you can use your right, which is called exercising the option.
• Premium : The price you pay for the option. The seller receives it.
• Contract multiplier : How many units one contract covers. A $3 premium per unit costs $300 if the contract covers 100 units.
• Implied volatility (IV) : How much future price movement is priced into the option. All else equal, higher IV generally makes options more expensive.
• Settlement : How the contract delivers what’s owed. Cash settlement pays the difference in a specified currency. Physical settlement involves exchanging the underlying asset at the strike.
The strike tells you when the option starts paying. The premium tells you how much of that payout you need just to get your money back. That’s the difference behind the 7% rally in the opening.
—
● How an onchain options trade works
• Choose the contract
An asset trades at $100 and you think it will rise over the next month. You open the option chain, a list of calls and puts grouped by strike and expiry.
You choose a one-month call with a $105 strike. For this example, it covers one unit.
• Find a price and open the trade
You can trade against an offer on an order book or use a request for quote (RFQ) to ask market makers for a price.
An RFQ can also price several options together, which helps if you want the whole trade filled at once. Some venues also draw liquidity from automated market makers or vaults.
Your trade fills at $3. You pay the premium and the seller backs their obligation with collateral under the venue’s rules. Depending on the platform, matching can happen offchain while smart contracts manage collateral and settle the trade onchain.
• Sell early or hold to expiry
You can sell the call before expiry if there’s a buyer. Its resale price depends on where the asset trades, how much time is left, and implied volatility. Even if the asset rises, the call can lose value if the effect of time passing or falling IV is bigger than the effect of the rally.
• Calculate what you get at expiry
You hold the call and the asset settles at $107.
- Payout : $107 settlement price − $105 strike = $2
- Net result : $2 payout − $3 premium = −$1
- Breakeven : $105 strike + $3 premium = $108 before fees
The call was in the money because the asset settled above $105. But you needed $108 to recover the full premium. If the asset had settled at or below $105, the call would have paid zero.
—
● Why use options when perps already exist?
The call shows how the strike can limit what you earn from a rally. A put shows why choosing a strike can be useful when you already own the asset.
Say you hold the asset at $100 and want protection below $90 for one month. You buy a one-month $90 put. If the asset settles at $75, the put pays $15. That offsets the drop from $90 to $75. You still absorb the first $10 of the decline and the premium you paid for protection.
A short perp can also offset a decline while it’s open. It has no expiry, funding can add to or reduce the cost of holding it, and a leveraged position can be liquidated if margin falls too low.
The put gives you a specific level where protection starts and a date when it ends. That ability to choose the payoff is also what lets traders build spreads or trade a view on volatility.
—
● What makes onchain options harder to trade?
• Liquidity is spread across contracts.
A perp can concentrate trading in one market. Options divide it across calls, puts, strikes and expiries. One contract can trade easily while the one next to it barely has a bid. Asking for a quote can help, but market makers can decline.
• Timing matters.
A rally can come after expiry or fall short of breakeven. If you plan to sell early, time decay and changes in IV affect what someone will pay for your option.
• Margin depends on the account.
A fully paid standalone long option limits the position’s loss to the premium before fees. Under portfolio margin, the venue evaluates the whole account and can liquidate long options as part of that process. Sellers can also face liquidation.
• Settlement follows the contract’s rules.
The venue may use a reference index or average prices over a window. That can give you a different settlement price from the last price you see on the chart.
—
● Why use options when perps already exist?
The call example showed how the strike affects your payout. A put shows how you can use that same feature to protect an asset you already own.
Say you hold an asset at $100 and want protection below $90 for the next month. You buy a one-month $90 put. If the asset settles at $75, the put pays $15. You still take the first $10 of the drop and pay the premium, but the put covers the rest of the decline.
A short perp can also offset a drop while it’s open. It has no expiry, funding can add to or reduce your costs, and the position can be liquidated if your margin falls too low.
The put gives you a hedge with a specific price level, an end date and an upfront cost. Those same choices let traders combine options into spreads or trade a view on how much an asset might move.
—
● What makes onchain options harder to trade?
• The flexibility comes with a trade-off.
A perp can concentrate trading in one market. Options spread it across calls, puts, strikes and expiries. One contract might be easy to trade while the next barely has a bid. You can ask market makers for a quote, but they may decline.
• The trade also depends on how far the asset moves and when.
A rally can come too late or fall short of breakeven. If you want to sell early, the time left and changes in implied volatility affect what someone will pay for your option.
• A fully paid standalone option can lose up to the premium before fees.
Under portfolio margin, the platform looks at the whole account and may liquidate positions, including options you bought. Option sellers can also face liquidation.
• And if you hold to expiry, the payout depends on the platform’s settlement price.
That could be an index price or an average over a set period, so it may differ from the last price on your chart.
—
I am hoping this explains how the projects highlighted in this landscape operate.


Crypto derivatives have scaled around perpetual futures, but onchain options remain one of the market's most underdeveloped segments.
Despite reaching $1.77B in notional open interest, options liquidity and execution remain concentrated across a handful of venues.
As new protocols compete to close this gap, the next phase of growth will depend on how effectively they solve liquidity, execution and capital efficiency.
Here's a look at the emerging onchain options landscape.
—
● The Liquidity Gap Between Perpetuals and Options
Perpetual futures have become crypto's dominant derivatives product, while options remain comparatively underdeveloped despite their widespread adoption in traditional finance.
The contrast is significant:
• Traditional finance: Options reportedly trade 3x more contracts than futures.
• Crypto: Perpetual futures reportedly generate 238x more volume than options.
Crypto perpetual futures have recorded $18T in all-time volume, compared with just $75.5B for options.
This gap highlights the potential for options to capture a larger share of derivatives activity. However, unlike perpetuals, options require liquidity across multiple strikes, expiries and contract types.
That fragmentation makes execution and market-making considerably more difficult.
—
● RFQ: Bringing Institutional Liquidity Onchain
One approach to overcoming fragmented options liquidity is Request for Quote (RFQ), which allows traders to source prices directly from professional market makers rather than relying entirely on resting order-book liquidity.
The process:
• A trader requests a quote for a specific options contract.
• Multiple market makers assess the risk and submit competing prices.
• The trader compares available quotes and accepts the preferred execution.
Trader request -> Market makers compete -> Quote accepted -> Trade executed
RFQ is particularly valuable for options because it can aggregate liquidity across market makers without requiring deep order books for every strike and expiry.
Alongside portfolio margin and structured execution, this model is becoming an important component of the emerging onchain options market.
—
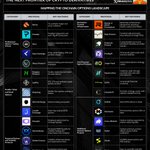
● Mapping the Onchain Options Landscape
The ecosystem is developing across several segments, with protocols addressing different aspects of trading, liquidity provision, volatility exposure and structured yield.
● Professional Options Trading Venues
These platforms focus on building the execution infrastructure required for sophisticated options trading.
• @DeriveXYZ: V3, portfolio margin and cross-collateral.
• @paradex: Paradigm integration and multi-leg RFQ execution.
• @aevoxyz: Options and perpetual futures, with PERPS+ linking options strategies to perp positions.
• @KyanExchange: Order-book trading, RFQ and portfolio margin.
• @IthacaProtocol: Options trading and structured strategies.
● Smaller-Ticket and Retail Options
While professional venues prioritize advanced execution, another group of platforms aims to make options accessible to a broader audience through smaller contracts and simplified trading interfaces.
• @SynapseProtocol: Smaller trade sizes and retail-focused options trading.
• @CallPutApp: BTC, ETH and synthetic equity options on Base.
• @dreaming: Mobile-first options trading on Solana.
• @Olive_Exchange: Options trading ecosystem.
• @JoyrideExchange: Same-day expiry options (0DTE).
These products address accessibility, but broader retail adoption will still depend on pricing, liquidity and manageable trading costs.
● Yield-Focused Options Products
Beyond active trading, options can also support structured yield strategies.
These protocols package options exposure into vaults and financial products, allowing users to participate without continuously managing individual positions.
• @ryskfinance: Covered calls and cash-secured puts through RFQs.
• @ThetanutsFi: Customizable options structures and direct liquidity-provider quotes.
• @ProdigyFi: Structured yield vaults built around market volatility.
• @jaspervault: Automated options strategy vaults.
• @hypersurfaceX: Volatility yield through covered calls and cash-secured puts.
• @SOFAorgDAO: Structured financial products.
• @chamberfi: Onchain strategy vaults with options-related activity.
This segment expands the use of options beyond speculation into income generation and automated risk management.
● Perpetual Options and Volatility Protocols
Other protocols are experimenting with alternative derivatives designs that reduce reliance on traditional expiry-based contracts or provide more direct exposure to volatility.
• @Panoptic_xyz: Perpetual options built on Uniswap liquidity.
• @GammaSwapLabs: Perpetual options using borrowed AMM liquidity to trade volatility and hedge impermanent loss.
• @SmileeFinance: Volatility-linked derivatives and Impermanent Gain products.
• @DeriProtocol: Everlasting options and other onchain derivatives.
• @volmexfinance: BTC and ETH implied-volatility indices.
These models introduce new ways to trade volatility, manage risk and access options-like exposure without relying exclusively on conventional options markets.
● Derivatives-Focused Infrastructure
Alongside trading protocols, blockchain infrastructure is also being developed to support more specialized derivatives activity.
• @RCKTFoundation: Rocket L1, designed for onchain perpetual futures, options and RWAs.
● Additional Onchain Options Projects
Several other projects provide, or have previously provided, options-related products through different trading models and blockchain ecosystems.
• @odetteonchain: Daily 0DTE options on Base.
• @stochastic_fin: Permissionless options DEX on Base.
• @ArrowMarkets: Options trading supported by market-maker liquidity.
• @optivixyz: Options protocol, with specific product details requiring further verification.
• @stryke_xyz: CLAMM-based options and RFQ trading.
• @HegicOptions: Peer-to-pool BTC and ETH options.
• @pacifica_fi: Solana-based perpetual futures exchange, included for derivatives ecosystem context rather than as a dedicated options platform.
Together, these projects show how the market is expanding beyond traditional options exchanges into retail trading, structured products, perpetual options and specialized infrastructure.
However, a growing number of platforms does not necessarily translate into deeper or more efficient liquidity.
—
● The Core Challenges Facing Onchain Options
Despite growing experimentation, four structural challenges continue to limit adoption.
• Liquidity fragmentation: Liquidity is distributed across strikes, expiries and contract types, making competitive pricing difficult.
• Multi-leg execution: Executing individual legs separately introduces execution risk and increases transaction costs.
• Capital inefficiency: Isolated margin requirements fail to account for portfolio-level hedging, increasing collateral demands.
• Trading costs: Fees, spreads and slippage make sophisticated options strategies expensive to execute.
RFQ systems, portfolio margin and smaller contracts address different parts of these challenges, but solving them collectively remains essential for sustainable market growth.
—
Perpetual futures established crypto's derivatives market, but options represent a largely underdeveloped layer with significant room for expansion.
Fractional contracts can lower entry barriers, while structured payoffs allow traders to access risk profiles that perpetual futures cannot easily replicate.
The opportunity extends beyond speculation into hedging, volatility trading and structured yield.
However, the next generation of onchain options will not be defined simply by the number of protocols entering the market.
The platforms that win will be those capable of combining competitive liquidity, reliable execution, capital efficiency and accessible risk management.
Ultimately, making options easier to trade and more useful will matter far more than simply making them available onchain.

You buy a call expecting the asset to rise. It rallies 7% by expiry, and you still lose money.
Sounds strange, right? The call paid out, but the payout was smaller than what you paid for it.
If you’re new to options, here’s Options 101. I’ll break down what you’re buying, how the trade works from start to finish, and when options make more sense than perps.
—
● Options 101: What are you actually buying?
An option gives you the right to buy or sell an asset at an agreed price. You can use that right if it benefits you or let it expire. The seller gets paid upfront for taking on the other side of that agreement.
Here are the terms you’ll see on an options platform.
• Underlying : The asset or reference price the option tracks.
• Call : The right to buy at the agreed price. A call pays at expiry if the asset settles above that price.
• Put : The right to sell at the agreed price. A put pays at expiry if the asset settles below that price.
• Strike : The agreed price. It determines where the option starts to pay at expiry.
• Expiry : The date and time the contract ends. The contract rules determine when you can use your right, which is called exercising the option.
• Premium : The price you pay for the option. The seller receives it.
• Contract multiplier : How many units one contract covers. A $3 premium per unit costs $300 if the contract covers 100 units.
• Implied volatility (IV) : How much future price movement is priced into the option. All else equal, higher IV generally makes options more expensive.
• Settlement : How the contract delivers what’s owed. Cash settlement pays the difference in a specified currency. Physical settlement involves exchanging the underlying asset at the strike.
The strike tells you when the option starts paying. The premium tells you how much of that payout you need just to get your money back. That’s the difference behind the 7% rally in the opening.
—
● How an onchain options trade works
• Choose the contract
An asset trades at $100 and you think it will rise over the next month. You open the option chain, a list of calls and puts grouped by strike and expiry.
You choose a one-month call with a $105 strike. For this example, it covers one unit.
• Find a price and open the trade
You can trade against an offer on an order book or use a request for quote (RFQ) to ask market makers for a price.
An RFQ can also price several options together, which helps if you want the whole trade filled at once. Some venues also draw liquidity from automated market makers or vaults.
Your trade fills at $3. You pay the premium and the seller backs their obligation with collateral under the venue’s rules. Depending on the platform, matching can happen offchain while smart contracts manage collateral and settle the trade onchain.
• Sell early or hold to expiry
You can sell the call before expiry if there’s a buyer. Its resale price depends on where the asset trades, how much time is left, and implied volatility. Even if the asset rises, the call can lose value if the effect of time passing or falling IV is bigger than the effect of the rally.
• Calculate what you get at expiry
You hold the call and the asset settles at $107.
- Payout : $107 settlement price − $105 strike = $2
- Net result : $2 payout − $3 premium = −$1
- Breakeven : $105 strike + $3 premium = $108 before fees
The call was in the money because the asset settled above $105. But you needed $108 to recover the full premium. If the asset had settled at or below $105, the call would have paid zero.
—
● Why use options when perps already exist?
The call shows how the strike can limit what you earn from a rally. A put shows why choosing a strike can be useful when you already own the asset.
Say you hold the asset at $100 and want protection below $90 for one month. You buy a one-month $90 put. If the asset settles at $75, the put pays $15. That offsets the drop from $90 to $75. You still absorb the first $10 of the decline and the premium you paid for protection.
A short perp can also offset a decline while it’s open. It has no expiry, funding can add to or reduce the cost of holding it, and a leveraged position can be liquidated if margin falls too low.
The put gives you a specific level where protection starts and a date when it ends. That ability to choose the payoff is also what lets traders build spreads or trade a view on volatility.
—
● What makes onchain options harder to trade?
• Liquidity is spread across contracts.
A perp can concentrate trading in one market. Options divide it across calls, puts, strikes and expiries. One contract can trade easily while the one next to it barely has a bid. Asking for a quote can help, but market makers can decline.
• Timing matters.
A rally can come after expiry or fall short of breakeven. If you plan to sell early, time decay and changes in IV affect what someone will pay for your option.
• Margin depends on the account.
A fully paid standalone long option limits the position’s loss to the premium before fees. Under portfolio margin, the venue evaluates the whole account and can liquidate long options as part of that process. Sellers can also face liquidation.
• Settlement follows the contract’s rules.
The venue may use a reference index or average prices over a window. That can give you a different settlement price from the last price you see on the chart.
—
● Why use options when perps already exist?
The call example showed how the strike affects your payout. A put shows how you can use that same feature to protect an asset you already own.
Say you hold an asset at $100 and want protection below $90 for the next month. You buy a one-month $90 put. If the asset settles at $75, the put pays $15. You still take the first $10 of the drop and pay the premium, but the put covers the rest of the decline.
A short perp can also offset a drop while it’s open. It has no expiry, funding can add to or reduce your costs, and the position can be liquidated if your margin falls too low.
The put gives you a hedge with a specific price level, an end date and an upfront cost. Those same choices let traders combine options into spreads or trade a view on how much an asset might move.
—
● What makes onchain options harder to trade?
• The flexibility comes with a trade-off.
A perp can concentrate trading in one market. Options spread it across calls, puts, strikes and expiries. One contract might be easy to trade while the next barely has a bid. You can ask market makers for a quote, but they may decline.
• The trade also depends on how far the asset moves and when.
A rally can come too late or fall short of breakeven. If you want to sell early, the time left and changes in implied volatility affect what someone will pay for your option.
• A fully paid standalone option can lose up to the premium before fees.
Under portfolio margin, the platform looks at the whole account and may liquidate positions, including options you bought. Option sellers can also face liquidation.
• And if you hold to expiry, the payout depends on the platform’s settlement price.
That could be an index price or an average over a set period, so it may differ from the last price on your chart.
—
I am hoping this explains how the projects highlighted in this landscape operate.
Crypto derivatives have scaled around perpetual futures, but onchain options remain one of the market's most underdeveloped segments.
Despite reaching $1.77B in notional open interest, options liquidity and execution remain concentrated across a handful of venues.
As new protocols compete to close this gap, the next phase of growth will depend on how effectively they solve liquidity, execution and capital efficiency.
Here's a look at the emerging onchain options landscape.
—
● The Liquidity Gap Between Perpetuals and Options
Perpetual futures have become crypto's dominant derivatives product, while options remain comparatively underdeveloped despite their widespread adoption in traditional finance.
The contrast is significant:
• Traditional finance: Options reportedly trade 3x more contracts than futures.
• Crypto: Perpetual futures reportedly generate 238x more volume than options.
Crypto perpetual futures have recorded $18T in all-time volume, compared with just $75.5B for options.
This gap highlights the potential for options to capture a larger share of derivatives activity. However, unlike perpetuals, options require liquidity across multiple strikes, expiries and contract types.
That fragmentation makes execution and market-making considerably more difficult.
—
● RFQ: Bringing Institutional Liquidity Onchain
One approach to overcoming fragmented options liquidity is Request for Quote (RFQ), which allows traders to source prices directly from professional market makers rather than relying entirely on resting order-book liquidity.
The process:
• A trader requests a quote for a specific options contract.
• Multiple market makers assess the risk and submit competing prices.
• The trader compares available quotes and accepts the preferred execution.
Trader request -> Market makers compete -> Quote accepted -> Trade executed
RFQ is particularly valuable for options because it can aggregate liquidity across market makers without requiring deep order books for every strike and expiry.
Alongside portfolio margin and structured execution, this model is becoming an important component of the emerging onchain options market.
—
● Mapping the Onchain Options Landscape
The ecosystem is developing across several segments, with protocols addressing different aspects of trading, liquidity provision, volatility exposure and structured yield.
● Professional Options Trading Venues
These platforms focus on building the execution infrastructure required for sophisticated options trading.
• @DeriveXYZ: V3, portfolio margin and cross-collateral.
• @paradex: Paradigm integration and multi-leg RFQ execution.
• @aevoxyz: Options and perpetual futures, with PERPS+ linking options strategies to perp positions.
• @KyanExchange: Order-book trading, RFQ and portfolio margin.
• @IthacaProtocol: Options trading and structured strategies.
● Smaller-Ticket and Retail Options
While professional venues prioritize advanced execution, another group of platforms aims to make options accessible to a broader audience through smaller contracts and simplified trading interfaces.
• @SynapseProtocol: Smaller trade sizes and retail-focused options trading.
• @CallPutApp: BTC, ETH and synthetic equity options on Base.
• @dreaming: Mobile-first options trading on Solana.
• @Olive_Exchange: Options trading ecosystem.
• @JoyrideExchange: Same-day expiry options (0DTE).
These products address accessibility, but broader retail adoption will still depend on pricing, liquidity and manageable trading costs.
● Yield-Focused Options Products
Beyond active trading, options can also support structured yield strategies.
These protocols package options exposure into vaults and financial products, allowing users to participate without continuously managing individual positions.
• @ryskfinance: Covered calls and cash-secured puts through RFQs.
• @ThetanutsFi: Customizable options structures and direct liquidity-provider quotes.
• @ProdigyFi: Structured yield vaults built around market volatility.
• @jaspervault: Automated options strategy vaults.
• @hypersurfaceX: Volatility yield through covered calls and cash-secured puts.
• @SOFAorgDAO: Structured financial products.
• @chamberfi: Onchain strategy vaults with options-related activity.
This segment expands the use of options beyond speculation into income generation and automated risk management.
● Perpetual Options and Volatility Protocols
Other protocols are experimenting with alternative derivatives designs that reduce reliance on traditional expiry-based contracts or provide more direct exposure to volatility.
• @Panoptic_xyz: Perpetual options built on Uniswap liquidity.
• @GammaSwapLabs: Perpetual options using borrowed AMM liquidity to trade volatility and hedge impermanent loss.
• @SmileeFinance: Volatility-linked derivatives and Impermanent Gain products.
• @DeriProtocol: Everlasting options and other onchain derivatives.
• @volmexfinance: BTC and ETH implied-volatility indices.
These models introduce new ways to trade volatility, manage risk and access options-like exposure without relying exclusively on conventional options markets.
● Derivatives-Focused Infrastructure
Alongside trading protocols, blockchain infrastructure is also being developed to support more specialized derivatives activity.
• @RCKTFoundation: Rocket L1, designed for onchain perpetual futures, options and RWAs.
● Additional Onchain Options Projects
Several other projects provide, or have previously provided, options-related products through different trading models and blockchain ecosystems.
• @odetteonchain: Daily 0DTE options on Base.
• @stochastic_fin: Permissionless options DEX on Base.
• @ArrowMarkets: Options trading supported by market-maker liquidity.
• @optivixyz: Options protocol, with specific product details requiring further verification.
• @stryke_xyz: CLAMM-based options and RFQ trading.
• @HegicOptions: Peer-to-pool BTC and ETH options.
• @pacifica_fi: Solana-based perpetual futures exchange, included for derivatives ecosystem context rather than as a dedicated options platform.
Together, these projects show how the market is expanding beyond traditional options exchanges into retail trading, structured products, perpetual options and specialized infrastructure.
However, a growing number of platforms does not necessarily translate into deeper or more efficient liquidity.
—
● The Core Challenges Facing Onchain Options
Despite growing experimentation, four structural challenges continue to limit adoption.
• Liquidity fragmentation: Liquidity is distributed across strikes, expiries and contract types, making competitive pricing difficult.
• Multi-leg execution: Executing individual legs separately introduces execution risk and increases transaction costs.
• Capital inefficiency: Isolated margin requirements fail to account for portfolio-level hedging, increasing collateral demands.
• Trading costs: Fees, spreads and slippage make sophisticated options strategies expensive to execute.
RFQ systems, portfolio margin and smaller contracts address different parts of these challenges, but solving them collectively remains essential for sustainable market growth.
—
Perpetual futures established crypto's derivatives market, but options represent a largely underdeveloped layer with significant room for expansion.
Fractional contracts can lower entry barriers, while structured payoffs allow traders to access risk profiles that perpetual futures cannot easily replicate.
The opportunity extends beyond speculation into hedging, volatility trading and structured yield.
However, the next generation of onchain options will not be defined simply by the number of protocols entering the market.
The platforms that win will be those capable of combining competitive liquidity, reliable execution, capital efficiency and accessible risk management.
Ultimately, making options easier to trade and more useful will matter far more than simply making them available onchain.
Crypto derivatives have scaled around perpetual futures, but onchain options remain one of the market's most underdeveloped segments.
Despite reaching $1.77B in notional open interest, options liquidity and execution remain concentrated across a handful of venues.
As new protocols compete to close this gap, the next phase of growth will depend on how effectively they solve liquidity, execution and capital efficiency.
Here's a look at the emerging onchain options landscape.
—
● The Liquidity Gap Between Perpetuals and Options
Perpetual futures have become crypto's dominant derivatives product, while options remain comparatively underdeveloped despite their widespread adoption in traditional finance.
The contrast is significant:
• Traditional finance: Options reportedly trade 3x more contracts than futures.
• Crypto: Perpetual futures reportedly generate 238x more volume than options.
Crypto perpetual futures have recorded $18T in all-time volume, compared with just $75.5B for options.
This gap highlights the potential for options to capture a larger share of derivatives activity. However, unlike perpetuals, options require liquidity across multiple strikes, expiries and contract types.
That fragmentation makes execution and market-making considerably more difficult.
—
● RFQ: Bringing Institutional Liquidity Onchain
One approach to overcoming fragmented options liquidity is Request for Quote (RFQ), which allows traders to source prices directly from professional market makers rather than relying entirely on resting order-book liquidity.
The process:
• A trader requests a quote for a specific options contract.
• Multiple market makers assess the risk and submit competing prices.
• The trader compares available quotes and accepts the preferred execution.
Trader request -> Market makers compete -> Quote accepted -> Trade executed
RFQ is particularly valuable for options because it can aggregate liquidity across market makers without requiring deep order books for every strike and expiry.
Alongside portfolio margin and structured execution, this model is becoming an important component of the emerging onchain options market.
—
● Mapping the Onchain Options Landscape
The ecosystem is developing across several segments, with protocols addressing different aspects of trading, liquidity provision, volatility exposure and structured yield.
● Professional Options Trading Venues
These platforms focus on building the execution infrastructure required for sophisticated options trading.
• @DeriveXYZ: V3, portfolio margin and cross-collateral.
• @paradex: Paradigm integration and multi-leg RFQ execution.
• @aevoxyz: Options and perpetual futures, with PERPS+ linking options strategies to perp positions.
• @KyanExchange: Order-book trading, RFQ and portfolio margin.
• @IthacaProtocol: Options trading and structured strategies.
● Smaller-Ticket and Retail Options
While professional venues prioritize advanced execution, another group of platforms aims to make options accessible to a broader audience through smaller contracts and simplified trading interfaces.
• @SynapseProtocol: Smaller trade sizes and retail-focused options trading.
• @CallPutApp: BTC, ETH and synthetic equity options on Base.
• @dreaming: Mobile-first options trading on Solana.
• @Olive_Exchange: Options trading ecosystem.
• @JoyrideExchange: Same-day expiry options (0DTE).
These products address accessibility, but broader retail adoption will still depend on pricing, liquidity and manageable trading costs.
● Yield-Focused Options Products
Beyond active trading, options can also support structured yield strategies.
These protocols package options exposure into vaults and financial products, allowing users to participate without continuously managing individual positions.
• @ryskfinance: Covered calls and cash-secured puts through RFQs.
• @ThetanutsFi: Customizable options structures and direct liquidity-provider quotes.
• @ProdigyFi: Structured yield vaults built around market volatility.
• @jaspervault: Automated options strategy vaults.
• @hypersurfaceX: Volatility yield through covered calls and cash-secured puts.
• @SOFAorgDAO: Structured financial products.
• @chamberfi: Onchain strategy vaults with options-related activity.
This segment expands the use of options beyond speculation into income generation and automated risk management.
● Perpetual Options and Volatility Protocols
Other protocols are experimenting with alternative derivatives designs that reduce reliance on traditional expiry-based contracts or provide more direct exposure to volatility.
• @Panoptic_xyz: Perpetual options built on Uniswap liquidity.
• @GammaSwapLabs: Perpetual options using borrowed AMM liquidity to trade volatility and hedge impermanent loss.
• @SmileeFinance: Volatility-linked derivatives and Impermanent Gain products.
• @DeriProtocol: Everlasting options and other onchain derivatives.
• @volmexfinance: BTC and ETH implied-volatility indices.
These models introduce new ways to trade volatility, manage risk and access options-like exposure without relying exclusively on conventional options markets.
● Derivatives-Focused Infrastructure
Alongside trading protocols, blockchain infrastructure is also being developed to support more specialized derivatives activity.
• @RCKTFoundation: Rocket L1, designed for onchain perpetual futures, options and RWAs.
● Additional Onchain Options Projects
Several other projects provide, or have previously provided, options-related products through different trading models and blockchain ecosystems.
• @odetteonchain: Daily 0DTE options on Base.
• @stochastic_fin: Permissionless options DEX on Base.
• @ArrowMarkets: Options trading supported by market-maker liquidity.
• @optivixyz: Options protocol, with specific product details requiring further verification.
• @stryke_xyz: CLAMM-based options and RFQ trading.
• @HegicOptions: Peer-to-pool BTC and ETH options.
• @pacifica_fi: Solana-based perpetual futures exchange, included for derivatives ecosystem context rather than as a dedicated options platform.
Together, these projects show how the market is expanding beyond traditional options exchanges into retail trading, structured products, perpetual options and specialized infrastructure.
However, a growing number of platforms does not necessarily translate into deeper or more efficient liquidity.
—
● The Core Challenges Facing Onchain Options
Despite growing experimentation, four structural challenges continue to limit adoption.
• Liquidity fragmentation: Liquidity is distributed across strikes, expiries and contract types, making competitive pricing difficult.
• Multi-leg execution: Executing individual legs separately introduces execution risk and increases transaction costs.
• Capital inefficiency: Isolated margin requirements fail to account for portfolio-level hedging, increasing collateral demands.
• Trading costs: Fees, spreads and slippage make sophisticated options strategies expensive to execute.
RFQ systems, portfolio margin and smaller contracts address different parts of these challenges, but solving them collectively remains essential for sustainable market growth.
—
Perpetual futures established crypto's derivatives market, but options represent a largely underdeveloped layer with significant room for expansion.
Fractional contracts can lower entry barriers, while structured payoffs allow traders to access risk profiles that perpetual futures cannot easily replicate.
The opportunity extends beyond speculation into hedging, volatility trading and structured yield.
However, the next generation of onchain options will not be defined simply by the number of protocols entering the market.
The platforms that win will be those capable of combining competitive liquidity, reliable execution, capital efficiency and accessible risk management.
Ultimately, making options easier to trade and more useful will matter far more than simply making them available onchain.
Demand for onchain equity exposure grew faster than the infrastructure for owning, trading and borrowing against stocks onchain.
That gap explains much of what happened this year. Issuers put more equities onchain, exchanges and wallets brought them to users, AMMs and memecoin pools gave stock tokens new roles.
But once those tokens started moving into lending markets, the questions got harder. Who holds the underlying shares? Who can redeem? And what happens when liquidity disappears?
Dive into this detailed 2026 tokenized stocks report to understand how stocks went mainstream this year and where they go from here.
—
● From the Tokenization Landscape to the Stock Token
The broader RWA landscape showed how much infrastructure sits behind an asset onchain. Issuers structure it, custodians hold the backing, trading venues provide liquidity, and data and lending protocols determine how it can be used across DeFi.
xitter.twitterapi.xyz/Marspective/status/203…
Stocks made those dependencies easier to see. Two tokens can track the same company while offering different rights. One can represent the share itself. Another can provide price exposure through a third-party instrument.
Both can trade under a recognizable ticker, but the structure behind each token determines what holders own and how they can use it.
xitter.twitterapi.xyz/Marspective/status/206…
—
● More Issuers, More Venues, More Fragmented Liquidity
As several issuers began offering exposure to the same stocks, liquidity split across wrappers, chains and venues. A familiar ticker could appear in multiple pools without those pools sharing depth.
Aggregators can help traders find the best available route, but different legal claims and redemption terms make it harder to treat every version of a stock as interchangeable.
xitter.twitterapi.xyz/Marspective/status/208…
That fragmentation made the design of individual markets more important. On Robinhood Chain, stock tokens paired directly with SPY showed where AMMs could have an edge.
Traders could move between correlated assets without routing every trade through dollars, while LPs could supply two assets they already wanted to hold.
Those pools recorded $33M in volume in 12 days, offering an early example of how tokenization can change the way equities trade.
xitter.twitterapi.xyz/Marspective/status/209…
Once those markets existed, distribution became a bigger source of advantage. Exchanges had users, wallets had direct access to them, and aggregators could route orders across venues.
As more issuers offered similar exposure, those channels increasingly shaped which stock tokens users encountered and where their trades landed.
xitter.twitterapi.xyz/Marspective/status/209…
—
● Trading Proved Demand but Lending Exposed the Gaps.
One snapshot put weekly tokenized-equity spot volume near $3B, while only around 5% of the market was deployed in DeFi. The two figures capture different things. Trading volume shows how much activity passes through a market.
DeFi deployment shows how much equity capital is being put to work in applications such as lending.
Accepting a stock token as collateral raises the bar. A lending protocol needs a reliable price, enough liquidity to liquidate a position, and a clear understanding of what can happen when the underlying stock market is closed or redemption is restricted.
xitter.twitterapi.xyz/Marspective/status/209…
The SEC framework covered in the series brought the legal side of that distinction into focus. The permissioned AMM pathway applied to qualifying securities that preserve shareholder rights.
Meanwhile, much of the onchain activity was already happening in wrappers built primarily for price exposure. The products drawing trading activity and the products built around shareholder rights were developing along different paths.
xitter.twitterapi.xyz/Marspective/status/210…
Memecoin pools showed how far those paths could diverge. By pairing memecoins with stock tokens, they gave traders a reason to use equity wrappers even when they came to trade something else.
Across 19 liquid wrappers in the sample, meme-quoted pools held roughly 17.2% of the onchain float. The question is how much of that liquidity can stay once speculative activity fades.
xitter.twitterapi.xyz/Marspective/status/210…
—
● Exposure Scaled Faster Than Ownership
Equity perps surpassed $590B in 2026 year-to-date trading volume by the time of the October analysis. That figure measures turnover in derivatives, but it shows how quickly crypto markets can distribute exposure to stocks.
Direct onchain ownership has more pieces to coordinate. Transfer agents and shareholder registers still matter, alongside voting rights, dividends, corporate actions and rules around who can hold or transfer the shares.
xitter.twitterapi.xyz/Marspective/status/210…
Custody and redemption bring that distinction down to what a holder can actually do. A token can be backed 1:1 while offering limited redemption access or no direct shareholder rights.
Selling on a DEX depends on available liquidity and redeeming through an issuer depends on eligibility, the product’s terms and what the holder can legally claim.
Those two exits can produce very different outcomes when markets are under stress.
xitter.twitterapi.xyz/Marspective/status/211…
—
● Where the Market Goes From Here
The first phase of tokenized stocks proved there was demand for equity exposure onchain. It also showed that issuance, distribution, liquidity and ownership can develop at very different speeds.
The next phase depends on whether those pieces can work together. A stock token becomes more useful when it can trade in a deep market, serve as credible collateral and give holders a clear claim they can enforce.
The strongest signal of progress will be how well those markets hold up when the underlying exchange is closed, liquidity is thin and holders need a reliable way out.

Two tokenized stocks can track the same share price while offering very different legal rights, custody protections, and redemption access.
Even 1:1 backing doesn't guarantee holders own the underlying shares or can redeem them on demand.
So what actually separates these products?
Let's break it down.
—
● The Infrastructure Behind Tokenized Stocks
Four layers connect traditional equities to onchain markets:
Traditional stock market -> Broker and custodian -> Issuer and legal structure -> Onchain token
Each layer serves a different purpose, making three distinctions important:
• Backing: Are the underlying shares actually held?
• Ownership: What legal rights does the token holder receive?
• Redemption: Can holders exchange tokens for cash or underlying shares?
A token can be fully backed without granting direct shareholder rights or unrestricted redemption.
Understanding this distinction starts with how shares become tradable tokens.
—
● How Tokenized Stocks Move From Shares to Redemption
The process generally follows four steps:
1. Acquire: The issuer or broker purchases and custodies the underlying shares.
2. Mint: Eligible participants complete KYC/AML checks before tokens are issued.
3. Trade: Tokens trade across supported CEXs or DEXs, depending on liquidity and restrictions.
4. Redeem: Eligible holders exchange tokens for cash, stablecoins or securities under the product's terms.
Importantly, holders have two potential exit routes:
• Secondary sale: Sell tokens to another buyer at the prevailing market price.
• Direct redemption: Return tokens to the issuer through its approved redemption process.
The distinction matters because selling requires market liquidity, while redemption requires issuer access.
—
● Tradable Doesn't Mean Redeemable
A token can remain freely tradable even when direct redemption is restricted by KYC/AML requirements, jurisdiction or wallet whitelisting.
Holders without redemption access must depend on secondary-market buyers to exit.
This creates another problem of limited arbitrage.
When eligible participants cannot freely mint or redeem, token prices can diverge from the underlying shares despite continued trading.
The result is that two products tracking the same stock can behave differently under market stress.
—
● Same Asset Exposure, Different Rights
Tokenized-stock providers use different legal and redemption structures.
• @xStocksFi: Supports cash redemption and an in-kind redemption route through xPort, subject to eligibility.
• @Ondo : Uses structured notes issued through a BVI SPV, with redemption governed by product terms.
• @RobinhoodApp: Offers Jersey-issued debt securities providing economic exposure rather than direct shareholder rights.
• @DinariGlobal: Redemption reportedly involves selling custodied shares and distributing proceeds to eligible holders.
• @MEXC: Lists third-party tokenized stocks alongside its separate RealStocks offering, without necessarily acting as issuer or custodian.
Although these products provide similar market exposure, their ownership claims, custody arrangements and redemption rights differ.
Current product terms remain essential for accurate comparisons.
—
● The Hidden Risk: Custody Concentration
Different issuers do not necessarily mean different custody arrangements.
Multiple tokenized-stock providers may depend on the same underlying broker or custodian.
This creates concentrated intermediary exposure, where holding several different tokens may provide less diversification than investors assume.
The next question is whether custody protections adequately address that risk.
—
● What Custody Protections Actually Cover
Several mechanisms aim to protect underlying assets, but they serve different purposes.
• Segregated accounts: Separate designated assets from others, subject to legal and insolvency rules.
• Security agents: May enforce collateral rights or liquidate assets under specified conditions.
• Proof of reserves: Verifies assets held at a particular moment, but doesn't establish unencumbered ownership or redemption rights.
None of these protections independently guarantees asset recovery if an issuer fails.
Their effectiveness ultimately depends on enforceable legal claims and the underlying custody structure.
—
● Redemption Access in Numbers
Reported industry data highlights the gap between token issuance and actual redemption access.
• ~880 tokenized-stock deployments reportedly existed as of August 2026.
• ~31 reportedly supported open issuer redemption, according to OnChain Benchmark.
• ~94% of tokenized US equity custody or clearing was reportedly linked to Alpaca Securities.
These figures require source verification, but they highlight two important questions: how widely redemption is available and how concentrated the underlying infrastructure has become.
—
● Where Stablecoins Fit Into the Picture
Stablecoins increasingly provide a settlement layer for tokenized financial assets, but their legal obligations remain distinct.
The GENIUS Act establishes rules covering payment stablecoin reserves, redemption and custody, with @USOCC involved in implementation.
While stablecoins can facilitate tokenized-stock settlement, stablecoin redemption rights do not extend automatically to the underlying equity tokens.
The reported January 18, 2027 effective date also requires confirmation against official OCC documentation before publication.
—
Tokenization makes equity exposure transferable onchain, but it doesn't eliminate the legal, custody and redemption structures supporting it.
As tokenized equities scale, adoption will depend on more than trading access or 1:1 backing.
The real test is whether holders can understand, exercise and enforce their rights when liquidity disappears or intermediaries fail.

Marspective retweeted

Can your tokenized stock become the real share?
You’ll find out here.
- About 5% is already the real share. I mean stocks issued by @SuperstateInc, @Securitize ($SECZ) and @fairmint. The token is the share, on the company's own register, kept by an onchain transfer agent.
- About 31% can swap into a share.
> @bstocksfinance can swap at Nest Trading. The share is held at @AlpacaHQ and only for eligible non-US users, inside Binance.
> @Backpack: swap at Backpack Securities into an entitlement. The share is held at RQD and you get a share at a broker, not your name on the register.
- About 60% can only become cash.
> @Ondo: redeem for USDon or USDC
> @xStocksFi: redeem with Backed, KYC, $5K minimum
> @RobinhoodApp: redeem for cash.
> @RealityFi_xyz: stablecoins, but not for most users.
> @DinariGlobal: redeem for funds.
- @coinbase says redeem but hasn't published how.
So, 36% can be, or become, a real share, 5% puts your name on the company's register, and 60% can only be sold or cashed out.
Owning the token isn't the same as owning the share.

Marspective retweeted

Nigeria is telling dollar-stablecoin issuers to go local or lose retail access.
To serve retail users, a dollar stablecoin now needs:
A Nigerian issuer
Local licences
Token approval
Existing operators need express interim permission during the transition.

The next phase of institutional RWA growth may depend less on tokenizing assets and more on building the financial infrastructure that makes them useful across DeFi.
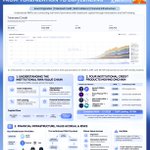
Four tokenized credit products already hold $1.05B in assets, with $619M represented across DeFi lending markets as of November 4, 2026.
Behind this growth is an emerging institutional value chain connecting real-world borrowers, asset originators, tokenization platforms, lending protocols and financial infrastructure.
Here's how the ecosystem works and where value is being captured.
—
● Understanding the Institutional RWA Value Chain
Institutional RWAs operate across four interconnected layers, each performing a different function in moving real-world credit onchain.
• Asset origination: Financial institutions create, underwrite and manage the underlying credit assets.
• Tokenization and distribution: Platforms structure these assets into investment products accessible to onchain capital.
• DeFi lending infrastructure: Protocols enable eligible RWA tokens to serve as collateral for borrowing and capital efficiency.
• Financial infrastructure: Stablecoin issuers, oracles and custodians support settlement, pricing and institutional access.
Together, these layers create a financing system connecting real economic activity with onchain liquidity.
—
● Layer 1: Asset Origination and Real-World Credit Demand
The foundation of institutional RWAs is the recurring demand for working capital.
Businesses often deploy capital before receiving payment, creating financing gaps across loans, receivables, payment settlements and commodity transactions.
The cycle is straightforward:
Deploy capital -> Finance the gap -> Complete transactions -> Collect payments -> Repay financing
Traditionally, businesses finance these gaps through banks, credit funds, receivables sales or securitization.
However, each comes with limitations ranging from expensive discounts and borrowing costs to restrictive underwriting and complex structuring.
Asset originators such as @Figure, @arf_one, @blackopal_fi, @TradeFlow_Algo and @apolloglobal operate within this credit ecosystem.
Their role is to originate or manage financing opportunities backed by real economic activity.
Tokenization creates an additional channel through which these assets can access capital.
—
● Layer 2: Tokenization and Onchain Distribution
Once credit assets are originated, they must be structured into investment products that onchain investors can access.
Businesses can raise funding against eligible loans or receivables through SPVs or secured financing arrangements.
Tokenization platforms then create digital representations of participation in these financing pools.
The capital flow looks like this:
Onchain investors -> Supply $USDC -> Financing vehicle -> Funds businesses -> Cash flows ->
Repayment and yield
Platforms such as @HastraFi, @humafinance, @NestCredit, @obligatecom, @Securitize, @Ondo, @SuperstateInc and @centrifuge operate across different parts of this tokenization and distribution layer.
The value proposition extends beyond putting assets onchain.
It involves making institutional credit accessible to new capital sources while preserving the legal and economic structures supporting repayment.
—
● Four Examples of Institutional Credit Moving Onchain
Four tokenized credit products demonstrate how this value chain is already connecting stablecoin liquidity with real-world financing.
As of November 4, 2026, their combined AUM reached approximately $1.052B.
• @HastraFi $PRIME + @Figure: $534M financing home equity loan warehouses.
• @humafinance $PST + @arf_one: $376M financing short-term cross-border payment settlements.
• @NestCredit $nOPAL + @blackopal_fi: $112M financing Brazilian card receivables.
• @obligatecom $oTFY + @TradeFlow_Algo: $30M financing commodity trade transactions.
Despite financing different economic activities, these products share a similar model.
Real-world credit generates the underlying cash flows, tokenization connects the assets to onchain investors, and DeFi integration creates opportunities for additional capital deployment.
—
● Layer 3: DeFi Lending and Collateral Utility
Tokenization gives investors access to real-world credit, but DeFi lending integration can significantly expand what those investments can do.
Instead of holding yield-bearing RWA tokens passively, investors can deposit eligible tokens as collateral and borrow stablecoins against them.
Protocols such as @Morpho, @kamino, @JupiterExchange Lend, @0xfluid and @aave provide infrastructure through which supported assets can access onchain borrowing markets.
This introduces a second source of demand beyond investors seeking direct exposure to real-world yield.
RWA tokens become productive collateral.
With $619M represented across DeFi lending markets among the four highlighted products, collateral utility is becoming an important part of their distribution model.
The competitive advantage increasingly shifts from simply issuing tokenized assets to securing their acceptance across liquid lending markets.
—
● The Leveraged Carry Trade Behind RWA Demand
The economic significance of lending integration becomes clearer through leveraged carry strategies.
Investors holding yield-bearing RWA tokens can borrow USDC against their positions and acquire additional yield-bearing assets.
The loop:
Buy RWA tokens -> Deposit as collateral -> Borrow USDC -> Acquire more RWA tokens
Consider an investor with $100K in equity who borrows another $100K to obtain $200K in exposure.
At an 8% asset yield and 5% borrowing cost:
• Gross yield: $16K
• Borrowing cost: $5K
• Net carry: $11K
This represents an 11% return on the initial $100K before fees and other costs.
The strategy creates additional demand for RWA collateral, but its economics depend on borrowing costs remaining below asset yields.
Leverage also introduces liquidation risk when collateral values decline.
—
● Layer 4: The Financial Infrastructure Supporting Institutional RWAs
The entire value chain depends on infrastructure that connects traditional financial assets with blockchain settlement.
Several providers support different parts of this process.
• Stablecoin settlement: @circle provides dollar-denominated liquidity infrastructure through USDC.
• Pricing and data: @chainlink and @PythNetwork support oracle infrastructure for asset valuation and market information.
• Custody and institutional access: @FireblocksHQ, @Anchorage and @BitGo support asset custody, security and institutional operations.
These services help bridge the operational differences between traditional credit markets and DeFi.
Without reliable settlement, pricing and custody, tokenized assets cannot easily function as institutional-grade collateral.
—
● Historical Precedent: Credit Markets Have Scaled This Model Before
Institutional tokenized credit is not an entirely new financial concept.
Traditional markets previously developed similar financing structures through asset-backed commercial paper (ABCP) and revolving receivables securitization.
ABCP expanded from approximately $40B in 1992 to nearly $1.2T by July 2007.
Credit-card securitization expanded in 1987, followed by Ford Credit's floor-plan securitization in 1991.
These structures connected short-term credit assets with institutional investors seeking yield.
Tokenization follows a similar economic principle but introduces stablecoins and DeFi lending as additional distribution and financing infrastructure.
The difference is how capital can move between investment products and lending markets.
—
● How the Institutional RWA Flywheel Develops
The interaction between these four layers creates a potential capital flywheel.
Real-world credit demand -> Asset origination -> Tokenized financing -> DeFi collateral acceptance -> Stablecoin borrowing -> Additional RWA demand
Businesses receive financing, originators gain additional funding channels, tokenization platforms attract capital, and lending protocols create collateral utility.
As more eligible RWA tokens enter lending markets, investors may become willing to allocate additional capital because the assets offer both yield and borrowing functionality.
However, the mechanism works in both directions.
Rising stablecoin borrowing costs, weakening collateral values or falling liquidity can force deleveraging and reduce demand for the underlying RWA tokens.
—
● Where Value Accrues and What Could Limit Growth
Each layer captures a different part of the institutional RWA opportunity.
Originators benefit from credit creation and servicing. Tokenization platforms facilitate issuance and distribution. Financial infrastructure providers support settlement and institutional operations.
But DeFi collateral acceptance could become one of the most important competitive advantages in the value chain.
It transforms tokenized credit from a passive yield product into an asset that can support additional borrowing and capital deployment.
That opportunity also introduces risks investors must evaluate.
• Legal exposure: Who is the actual borrower, and what recovery rights do token holders possess?
• Collateral protection: What advance rates, LTV limits, haircuts and default waterfalls protect the financing?
• Liquidity: Can token holders exit their positions if underlying credit assets cannot be redeemed immediately?
• Leverage sustainability: Can borrowing spreads remain attractive without creating excessive liquidation risk?
Ultimately, sustainable growth depends on both the quality of the underlying credit and the resilience of its onchain financing structure.
—
Institutional RWAs are evolving beyond the simple representation of traditional financial assets onchain.
A broader financial value chain is emerging, connecting real-world borrowers with stablecoin capital through origination, tokenization, DeFi lending and institutional infrastructure.
The next phase of RWA adoption may be defined by which platforms can connect these layers most effectively.
Tokenization brings real-world assets onchain. DeFi integration determines how efficiently those assets can be financed and used.
That distinction could shape where the next wave of institutional RWA value accrues.

L1 tokens are increasingly valued as monetary assets competing for capital, rather than businesses priced primarily on revenue.
Bitcoin beta explains 21–65% of four-week L1 returns, while on-chain fundamentals add just 0–9 percentage points.
But if network revenue explains so little, what actually determines which L1s capture lasting value?
—
● Understanding What Drives L1 Valuations
L1 valuations are shaped by two distinct forces operating across different time horizons:
• Short term: $BTC beta dominates token price movements, often outweighing changes in network fundamentals.
• Long term: The ability to attract and retain capital through stablecoins, DeFi TVL, tokenized RWAs, institutional investment and collateral demand shapes ecosystem positioning.
This helps explain why market capitalization can increase even as network revenue declines.
Investors are increasingly pricing an L1's monetary relevance and ability to attract capital, rather than its current economic output alone.
—
● Bitcoin Dominates Short-Term L1 Returns
@marcarjoon examined whether on-chain fundamentals explain L1 market movements beyond Bitcoin's price action, using REV, active addresses, DEX volume and stablecoin supply.
The findings show that BTC alone explains a substantial share of four-week L1 returns:
$ETH: 65% | $AVAX: 54% | $SOL: 51% | $BNB: 35% | $TRX: 21%
Adding all four on-chain metrics improves explanatory power by just 0–9 percentage points.
This suggests that while fundamentals matter, broader crypto market movements remain the dominant influence on short-term L1 returns.
—
● Why USD-Denominated Metrics Can Misrepresent Growth
One challenge in evaluating L1 fundamentals is that rising token prices can inflate reported revenue and TVL without any underlying increase in activity.
For example, 100 $ETH in fees increases from $200K to $400K when ETH doubles from $2,000 to $4,000, despite unchanged fee generation.
Similarly, TVL can rise through asset appreciation without fresh capital entering the ecosystem.
This makes native-unit REV particularly important for separating genuine economic activity from price-driven growth.
—
● Ethereum's Valuation Has Decoupled From Revenue
@Ethereum provides one of the clearest examples of why network revenue no longer fully explains L1 valuations.
Its trailing-12-month REV declined 60%, from $3.3B after Dencun to $1.3B by August 2025, while market capitalization increased from $460B to approximately $540B.
Much of this divergence reflects Ethereum's scaling strategy:
• EIP-4844 introduced cheaper blob transactions for L2s.
• Gas-limit increases expanded L1 blockspace, further compressing fees.
Rather than reducing Ethereum's monetary relevance, these changes coincided with growing institutional demand.
Spot ETFs and treasury-company accumulation attracted capital into ETH, increasingly supporting valuations beyond direct fee generation.
—
● Solana Shows a Stronger Revenue-Valuation Relationship
While Ethereum's valuation has diverged from network revenue, @Solana has historically shown a closer relationship between the two.
From January 2023 lows, both REV and market capitalization increased approximately 15x, reaching peaks of $2.5B and $130B, respectively.
Both subsequently declined:
• REV: $2.5B → $400M
• Market cap: $130B → $58B
This suggests that network economics have played a more visible role in $SOL's valuation.
However, the relationship remains imperfect, reinforcing that revenue is only one component of how markets price L1 assets.
—
● Why Metcalfe's Law Falls Short
If revenue alone cannot explain L1 valuations, can network adoption provide a better framework?
Metcalfe's Law suggests network value grows quadratically with its user base, but observed L1 relationships are considerably weaker.
ETH: 0.56 | SOL: 0.62 | $BNB: 0.62
Since 2016, BTC active addresses increased just 1.3x while market capitalization expanded 252x.
Similarly, ETH addresses increased 2.6x against 4.5x market-cap growth.
These differences suggest that user growth contributes to network value but cannot independently explain the scale of L1 valuations.
—
● REV Multiples Offer the Strongest Predictive Signal
Despite the limitations of revenue-based valuation, comparing six L1 valuation models revealed that market cap / REV provided the strongest predictive signal.
Two findings stand out:
• Lower valuations predicted stronger subsequent 13-week returns across $ETH and $TRON.
• Sector-wide ex-BTC market cap / REV expanded from approximately 50x in early 2022 to hundreds of times.
However, these multiples did not reliably mean-revert.
This suggests that REV remains useful for identifying relative valuations, even as investors increasingly assign premiums based on factors beyond current network revenue.
—
● Revenue Matters Most When Value Reaches Token Holders
The disconnect between revenue and valuation raises another important question: how much of a network's economic activity actually benefits its token?
Three examples illustrate different approaches:
• @NEARProtocol: Intents fees support token buybacks, yet NEAR trades at approximately 181x annualized REV compared with $TRON at 108x.
• @HyperliquidX: Derivatives revenue supports buybacks, creating a more direct connection between network activity and token-holder value.
• @trondao: Generates substantial network fees but trades at a comparatively lower REV multiple.
The distinction is important because generating revenue and transferring economic value to token holders are not necessarily the same thing.
Buybacks, burns and other accrual mechanisms can strengthen that connection.
—
Ultimately, L1 valuations reflect more than network revenue or user growth.
Bitcoin beta dominates short-term returns, while stablecoin liquidity, DeFi TVL, tokenized RWAs, institutional ownership and collateral demand increasingly influence where capital concentrates.
But attracting capital is only part of the equation.
The L1s best positioned to sustain long-term value are those that can retain capital while translating ecosystem activity into tangible token-holder value through fees, buybacks, burns and other accrual mechanisms.

Marspective retweeted

Crypto is hungry for real quantum progress.
I know because QuantumFi posts are printing the strongest mindshare, or at least mine did this quarter.
So here’s everything in one place, featuring 30+ protocols.
Web3 is evolving at lightning speed, and there’s clearly no shortage of new infrastructure being shipped.
Last week brought institutional transaction rails, tokenized-asset pricing, self-custodial cards, onchain credit, structured products, and new DeFi primitives. At the same time, major upgrades and new launches are setting up the next wave of activity.
Here’s what shipped last week and what’s coming next.
—
● Major Updates
• @StartaleApp launched Startale Card, expanding its consumer-facing crypto payments infrastructure
• @SentoraHQ launched Smart Yield Widgets, allowing crypto and fintech apps to embed yield/earn functionality directly into their own products
• @taliseio launched a USDsui-funded virtual card
• @VirtuneAB launched the Virtune AI Crypto Index ETP on Nasdaq Stockholm and Deutsche Börse Xetra
• @Yieldex_markets went live on @VoltaFamily
• @TenorFinance introduced Tenor Passive Quoting, allowing lenders to passively quote lend and exit rates across fixed-rate lending markets on Morpho Midnight
• @leapxyz introduced Leap, a self-custodial trading app
• @injective launched Institutional Rail, a dedicated transaction-access layer for banks, funds and enterprises
• @StandX_Official opened claims for the DUSD airdrop
• @JupiterExchange launched Combos for Jupiter Predict, bringing multi-outcome prediction-market trading onchain, powered by @Polymarket
• @okx launched its self-custodial stablecoin card in the US
• @tradeparagon introduced Power Perps, a move to bring options-like convexity into perpetual contracts
• @chainlink rolled out Chainlink 24/7, extending pricing for tokenized stocks and other traditional assets beyond traditional market hours
• @Splash_Wallet integrated Robinhood Chain, expanding access to DeFi activity on the network
• @benchdotmarkets introduced Trust Tokens, an onchain reputation-based credit and liquidity infrastructure
• @StellarOrg activated Protocol 30 “Bell” on testnet
• @LidoFinance integrated @Firelightfi’s onchain cover to add an automated, onchain loss-protection layer to Lido Earn
• @Ondo Intelligent Portfolios went live on @near_intents
• @okx launched Simple Options on tokenized stocks, a European-style options product that lets traders express directional or hedged views on equity markets 24/7
• @base activated its fourth major upgrade, Denim, on mainnet
• @Enter_Elysium’s L2 mainnet launches on @HyperliquidX on the 9th
• @SynapseProtocol is launching an Anthropic-linked options market on the 9th, offering 24/7 trading around Anthropic-related exposure
• @enjin launches its Fort Canning upgrade on Relaychain on the 9th
• @binance shuts down Binance Pool and related services on the 10th
• @tari scheduled its Ootle L2 mainnet launch for the 11th
• @blur_io’s frontend will be deprecated on the 12th
—
● Upcoming TGEs
• @morifinance_ ($MORI sale) - 9th
• @SlopCash ($SLOP trading) - 10th
• @namidefi ($NAMI TGE) - 10th
—
● Upcoming Token Unlocks
• @AlloraNetwork (200.5M $ALLO) - 10th
• @Rain__Protocol (24.64B $RAIN) - 10th
• @puffer_finance (22.77M $PUFFER) - 14th
• @SeiNetwork (119.86M $SEI) - 15th
• @Sign (298.24M $SIGN) - 15th
—
● Recent Milestones Across Protocols
• @INFINIT_Labs’ APEX Multi-Strategy Phase 2 surpassed $2M in total deposits
• @Ondo surpassed $4B in TVL and became the world’s largest tokenization platform
• @StellarOrg hit $5B in total RWA value
—
● Yield Opportunities To Explore This Week
• Protocol - @monetrix_xyz
• Network - @HyperliquidX
• Steps
➊ Visit monetrix.xyz/app/earn
➋ Mint mxHYPE using $HYPE
➌ Stake mxHYPE for smxHYPE
• Current yield - 8.73% APY
• Protocol - @SceptreLS
• Network - @FlareNetworks
• Steps
➊ Visit app.sceptre.fi/flare#stake
➋ Stake $FLR using sFLR
• Current yield - 7.78% APY
• Protocol - @glifio
• Network - @Filecoin
• Steps
➊ Visit glif.io/en/pool/infinity
➋ Stake $FIL to receive iFIL
• Current yield - 4.94% APY
—
That’s all for the week. Stick around for more updates weekly.

Marspective retweeted

Elysium Public Mainnet goes live tomorrow, but why wait until then to explore the ecosystem? 👀
We have been building and putting things in place ahead of launch to make your Day 1 experience easier.
Now it's your turn to get familiar with Elysium, explore what's being built, and get ready for what's ahead.
Don't show up on launch day as a stranger.
Bridge to Elysium:
elysianpad.fun


Marspective retweeted

Intel gives you a quant-level data for HL (currently in closed access). Insane amount of real-time data on who's doing what in the market.
I've got 10 codes for it. DM if you're on HL and want it.
(Or reply under the tweet).

Web3 is evolving on multiple fronts, from smarter security and better market infrastructure to new ways of building, earning, and creating value.
This week’s article roundup covers a range of ideas across Web3, including pre-IPO perps, vault security, tokenized equities, airdrop opportunities, and AI-driven businesses.
Several articles also explore how creators, founders, and professionals can adapt to changing market conditions.
Here’s a roundup of the interesting reads from the week.
—
@Baheet_ examines how pre-IPO perps can accurately forecast valuations while still being exposed to serious oracle risks.
Markets like SpaceX and Cerebras showed strong price discovery, but many perps rely partly on their own trading activity for reference prices, creating a self-referencing loop.
A bad external feed, corporate actions, or thin short-side liquidity can distort the oracle and trigger liquidations, which is why pre-IPO perps need an independent, liquid price source.
x.com/baheet_/status/2117178…
—
@Cryptfancier stresses that clear quality standards are vital for making decentralized labor marketplaces trustworthy for both contributors and projects.
Defined requirements, consistent evaluation, validation records, and real feedback separate genuine work from noise. @TheDAOLabs is pushing this further by automating more of the process.
The real gap sits between basic compliance, contribution quality, and campaign results. Stronger reporting and validation are still needed to turn activity rewards into a marketplace that reliably delivers useful work.
x.com/cryptfancier/status/21…
—
@zaimiri shares a practical framework for growing on X, centered on a clear profile, focused topics, strong hooks, valuable replies, and consistent posting.
The strategy is to make your page easy to understand, reply to relevant accounts, show the person behind the content, and study your best-performing posts to repeat what works.
For monetization, he recommends building credibility first, diversifying income across payouts, affiliates, brand deals, services and products, and maintaining a posting routine you can sustain.
x.com/zaimiri/status/2118661…
—
@definikos compares the permission and security models of @veda_labs, @ConcreteXYZ, @centrifuge and @upshift_fi.
Across the 4, the biggest risk sits with admin keys that can expand whitelists or change strategies, while timelocks often exclude the frequent changes that can expand a vault’s blast radius.
The takeaway is that secure vaults should pin recipients, delay mandate-widening changes past the exit window, separate pricing and execution keys, and give independent guardians the power to pause or veto risky changes.
x.com/definikos/status/21184…
—
@wizofecom shares a 90-day framework for building a founder’s personal brand on X.
The strategy combines articles, Google Doc screenshots, infographics, industry opinions, founder stories, and client results, with each content format serving a specific purpose across awareness, authority, and conversion.
Build content around your ideal customer profile, repurpose strong ideas across formats, and measure success by qualified leads and revenue, not just impressions and followers.
x.com/wizofecom/status/21187…
—
@steinRWA breaks down 6 ways to hold shares and shows how each structure decides whether you are a registered shareholder or just hold a claim through an intermediary.
It compares traditional certificates, broker-held shares, DRS, DSPPs, tokenized wrappers, and issuer-sponsored tokens, covering differences in ownership rights, dividends, voting, lending, and DeFi utility.
Not every tokenized stock equals real share ownership. Check whose name sits on the official register and what legal rights the tokens actually give you.
x.com/steinrwa/status/211656…
—
@FabianoSolana lists 20+ Solana airdrop opportunities, ranking projects across RWA, DeFi, trading, payments, mobile, and DePIN by farming potential.
He covers practical ways to earn points through trading, lending, liquidity, vaults, card use, and ecosystem activity, while flagging live campaigns and upcoming airdrops.
He advises to weigh timing, capital needs, competition, product quality, and risk before farming. A big funding round or points campaign alone doesn’t guarantee a worthwhile airdrop.
x.com/fabianosolana/status/2…
—
@jackhcable reviews recent major security incidents, including the $6.34B Binance theft, a compromised dev extension, and critical flaws in popular software.
AI is making attacks faster and cheaper, yet most breaches still exploit the same old weaknesses such as unpatched systems, stolen credentials, exposed secrets, and compromised developer devices.
Use phishing-resistant MFA, tighten device and extension controls, keep production secrets off dev machines, and ensure dependency audits, code scanning, and stronger monitoring.
x.com/jackhcable/status/2117…
—
@VibeMarketer_ outlines 5 one-person business models that lean on AI, including founder-led content, product-demo videos, niche research, small-business software, and AI automation services.
For each, he covers what to sell, how AI supports delivery, how to create a sample, and how to land the first customer.
Start with a problem you know well, validate a small paid offer, then use AI to make delivery repeatable while keeping human oversight on quality and client relationships.
x.com/vibemarketer_/status/2…
—
@ByRubiks argues that staying valuable in the AI era means adapting without constantly discarding the expertise you’ve built.
AI can automate tasks and make less experienced workers look more capable, but deep knowledge still matters for spotting errors, exercising judgment, and handling unfamiliar problems. Higher productivity also doesn’t automatically mean higher value or better pay.
The edge comes from building real expertise, knowing what’s being automated, and finding where that knowledge still solves valuable problems.
x.com/byrubiks/status/211870…
—
That’s a wrap for the week. Stick around for more insights weekly.


Finding sustainable yield opportunities in DeFi increasingly comes down to having access to structured strategies that can navigate different market conditions.
@Infinit_Labs is bringing that approach to onchain yield through its APEX Multi-Strategy Vaults, with Phase 2 already attracting over $2M in deposits.
Following Vault 1's reported ~34% gross APR, Vaults 2 and 3 are now live, offering access to the same CTA momentum strategy designed to capture market trends while managing volatility.
Here's what's available:
• Vault 2: 90-day trading period
• Vault 3: 30-day trading period
Both vaults follow the same underlying strategy, giving depositors flexibility to choose their preferred trading duration.
With over $2M already deposited into Phase 2, interest is building, and there's still an opportunity to participate.
Deposits remain open for just one more week, closing on November 11 at 12:00 UTC.
If you've been exploring opportunities to put your stablecoins to work through systematic trading strategies, APEX Multi-Strategy is worth a closer look.
Explore the vaults and deposit: app.infinit.tech
Disclaimer: Past performance is not a guarantee of future returns, and vault strategies carry risk.
🤝 Paid partnership

Binance's reported $6.3B security breach in October 2026 and Bybit's $1.4B hack in February 2025 have renewed concerns about centralized exchange security.
Both incidents exposed the risks of concentrating billions in user assets within exchange-controlled infrastructure.
But does moving trading onchain actually make Perp DEXs safer?
Let's compare where the risks sit.
—
● The Three Layers of Exchange Security
Comparing CEXs like @binance and @Bybit_Official with Perp DEXs like @HyperliquidX, @Lighter_xyz, @Aster_DEX and @variational_io requires looking beyond who holds user funds.
Three dimensions determine how secure an exchange really is:
• Custody: Who controls user funds and withdrawals?
• Protocol security: Can infrastructure or smart-contract vulnerabilities compromise execution?
• Market integrity: Can oracle manipulation or liquidation failures create losses?
CEXs concentrate operational control within exchange operators, while DEXs distribute dependencies across smart contracts, validators and supporting infrastructure.
The distinction becomes clearer when examining how recent exchange breaches occurred.
—
● Binance's $6.3B Breach: Internal Infrastructure Compromised
On October 29, 2026, Binance suffered a security breach involving unauthorized hot-wallet withdrawals. Rather than exploiting a smart-contract vulnerability, attackers compromised developer devices and internal wallet infrastructure to gain access to signing operations.
The attack developed over several months:
• June–September: Developers were targeted through malicious software and a fake job interview.
• October 20: Attackers gained access to developers' systems.
• October 29: Unauthorized withdrawals were executed.
• October 31: The FBI attributed the attack to North Korea's TraderTraitor group.
Binance committed to absorbing the losses through SAFU and corporate funds.
The incident highlights how compromised internal infrastructure can bypass security controls even without directly stealing wallet private keys.
—
● The Attack That Bypassed Bybit's Multisig
Bybit's February 21, 2025 hack exposed a different weakness within centralized custody.
Attackers stole approximately $1.4B in $ETH by compromising the exchange's Safe wallet signing interface.
Three authorized signers approved what appeared to be a legitimate transaction, but malicious JavaScript had altered its underlying instructions, allowing attackers to take control of the cold wallet.
The contrast:
• Binance: Developer infrastructure compromise enabled unauthorized hot-wallet transfers.
• Bybit: Signing interface compromise enabled a cold-wallet takeover.
Despite different attack methods, both incidents demonstrate that cold storage and multisig cannot eliminate operational security risks.
Understanding why requires examining how CEX custody works.
—
● How CEX Custody Works
Centralized exchanges manage user balances and perpetual positions through internal ledgers, while deposits and withdrawals settle onchain.
User deposit -> Internal ledger -> Hot / cold wallets -> Blockchain withdrawal
Three components support this architecture:
• Hot wallets: Online wallets handling operational transfers and withdrawals.
• Cold wallets: Offline storage designed to protect larger reserves.
• MPC / multisig: Systems that distribute transaction-signing authority.
However, this structure introduces two important dependencies.
• The Internal Ledger Risk:
Perpetual positions, collateral balances and PnL are recorded internally rather than through individual onchain transactions.
Users therefore depend on the exchange's accounting accuracy, operational security and withdrawal infrastructure.
• Proof of Reserves ≠ Proof of Solvency:
Merkle-based PoR can help users verify balances included in a reported liability snapshot.
However, it does not independently establish that all liabilities are disclosed or that reserves are free from encumbrances.
Perp DEXs attempt to reduce these dependencies, but their architecture introduces different risks.
—
● Perp DEX Architecture: Where Trust Moves
Unlike CEXs, Perp DEXs can hold collateral in smart contracts, reducing reliance on exchange-controlled wallets.
However, trading execution may still depend on centralized infrastructure.
User wallet -> Collateral -> Trading engine -> Oracle -> Liquidation -> Settlement
Three risks remain:
• Sequencer: Transaction censorship, delays or reordering.
• Oracle: Manipulated or stale prices affecting positions and liquidations.
• Smart contracts: Exploits, vulnerabilities or unauthorized upgrades.
The important distinction is that non-custodial does not automatically mean decentralized.
Users may retain control over collateral while operators still influence execution, protocol upgrades and emergency interventions.
How these responsibilities are distributed varies considerably across Perp DEXs.
—
● Protocol-by-Protocol Security Analysis
• @HyperliquidX
Hyperliquid operates a custom L1 using HyperBFT consensus, validator-operated infrastructure and an onchain order book.
• Validators aggregate external exchange prices to determine oracle feeds.
• The March 2025 JELLY incident left HLP with approximately $12M in unrealized losses.
• Validators intervened to delist the market, highlighting the trade-off between protecting the system and retaining discretionary control.
• @Lighter_xyz
Lighter uses an Ethereum-based zk-rollup architecture, applying cryptographic proofs to exchange execution.
• ZK proofs verify matching and liquidation state transitions.
• Its fallback mechanism is designed to support withdrawals if the sequencer fails.
• However, execution proofs cannot guarantee oracle accuracy or eliminate sequencer censorship.
• @Aster_DEX
Aster combines order-book trading with private order execution.
• Encrypted orders reduce public visibility into trading activity and large positions.
• The trade-off is less public transparency into execution.
• Security therefore depends partly on encryption assumptions and the scope of administrative permissions.
• @variational_io
Variational uses peer-to-peer derivatives with isolated settlement pools between users and the OLP.
• Isolated pools help limit direct contagion between users.
• However, OLP counterparty exposure and oracle risks remain.
• The protocol lists security audits by @zellic_io and @spearbit.
These differences show that Perp DEX security cannot be evaluated through custody alone.
Oracle reliability and liquidation mechanisms are equally important.
—
● Oracle Design and Liquidation Risk
Even when user collateral is protected by smart contracts, manipulated price feeds can trigger liquidations without corresponding movements in external markets.
For example:
$BTC market price: $100K -> Oracle reports $90K -> Leveraged long liquidated.
Three factors influence oracle resilience:
• Independence of price sources.
• Aggregation methodology and update frequency.
• Stale-feed protection and deviation limits.
Using multiple price sources is not sufficient on its own. Their independence, underlying liquidity and assigned weighting determine how resistant the oracle is to manipulation.
But accurate pricing is only one part of managing leveraged positions.
—
● Liquidation and Bad-Debt Risk
When market volatility pushes leveraged positions into insolvency, liquidation design determines how losses are contained and who ultimately absorbs them.
Different architectures use different mechanisms:
• CEXs: Internal liquidation engines, insurance funds and auto-deleveraging (ADL).
• Perp DEXs: Liquidators, backstop vaults, insurance funds or socialized-loss mechanisms.
• Both: Open-interest caps and position limits can help contain concentrated exposure.
This creates another important distinction between technical security and financial resilience.
A protocol can execute its smart contracts exactly as designed and still experience substantial losses because its liquidation economics fail under stress.
—
The Binance and Bybit breaches demonstrate the risks of concentrating custody and operational control within centralized exchanges.
Perp DEXs reduce certain custody dependencies, but shift security risks toward smart contracts, validators, oracles, execution infrastructure and liquidity backstops.
Neither architecture eliminates trust or the possibility of failure.
Ultimately, the question isn't simply whether CEXs or Perp DEXs are safer. It's where control sits, whether users can exit when something breaks, and who ultimately absorbs the losses when security mechanisms fail.
