
Partner at Altimeter Capital. Dad to 4 amazing kids. No investment advice, all views personal
San Francisco, CA
Joined September 2015
- Tweets6.7K
- Following1.5K
- Followers94.2K
- Likes17.3K




Pinned Tweet
Next up on First Pass: A conversation with @lorenc_dan from @chainguard_dev
We had one of the worst weeks ever in new security vulnerabilities discovered. What does the PHP vulnerability mean, how can companies prepare, what should we expect in the future, etc
We dig in!
Anthropic new models out today - Fable 5.2 and Mythos 5.2
Fable 5.2 available today at $8 per million input tokens and $40 per million output tokens
Seeing a reduction in frontier pricing!

Awesome to see @ClickHouseDB continue to push the product frontier.
- Deeper into OLTP
- Deeper into natural applications built on top of Clickhouse (Observability and Security / SIEM)
- Deeper into the AI gateway space

Today we’re announcing the largest expansion of ClickHouse since we launched ClickHouse Cloud, and we’re welcoming the @xata team to ClickHouse.
ClickHouse now serves more than 5,000 customers, including DoorDash, Ramp, Meta, Tesla, Cisco, and Visa. What began as an open source analytical database is now a platform for the full set of data-intensive workloads behind modern applications.
Launching today 🚀
ClickHouse Managed Postgres is generally available.
ClickHouse Observability is in public beta.
ClickHouse Security is in private preview.
Langfuse AI Gateway is in public beta.
And with the acquisition of Xata, the agent-native Postgres company, we’re accelerating instant branching, cloning, and scale-to-zero environments for developers and AI agents. Welcome, Xata!
One open, composable foundation to build, observe, and secure applications.
Read the full announcement: clickhouse.com/campaigns/pla…
This was fun!

What are the most important and most misunderstood lessons from the @AnthropicAI S-1?
What can we learn about the relative economics of neolabs and neoclouds, and how sustainable is Anthropic's edge over rivals in the most competitive market on earth!
Will $ANT even IPO?
We asked @jaminball of @AltimeterCap and Clouded Judgement, to walk engineers through the S-1:
youtu.be/P735f1xlpL0
What's your % odds on IPO. above $1.5T this year?

3
23
9,815

Next up on First Pass - a conversation with Arya (@a_a) from @SierraPlatform on their Personal Agent Protocol
Personal agents are taking over, and we need more streamlined ways for the services / products / websites we use to interact with personal agents
The world needs provable inference

@AnthropicAI is recognizing the importance of provable inference, and naming @attestable as the state of the art!
We are the only practical solution in the market that also support floating points, and there's much more exciting stuff coming soon!
anthropic.com/research/prova…

Provable inference is coming. A very real commercial use case for zero knowledge proofs is forming!
"Recently commercial efforts have reached impressive numbers, with Attestable proving Gemma 4 31B at 53–77 tok/s on a single H100"
cc @attestable
anthropic.com/research/prova…

Cloud Giants Update:
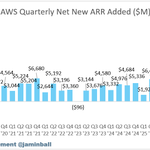
AWS (Amazon): $184B run rate growing 39% YoY (last Q grew 37%)
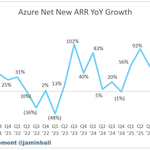
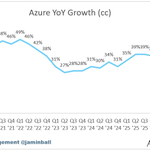
Azure (Microsoft): ~$138B run rate (estimate) growing 48% YoY (last Q grew 43%)
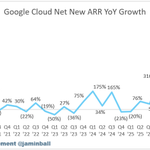
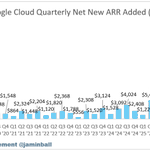
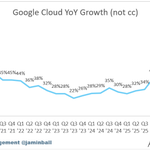
Google Cloud (includes GSuite): $123B run rate growing 103% YoY (last Q grew 82%, neither are cc)

Google Cloud at a ~$123B run rate growing 103%
Quarterly YoY growth trends below $GOOG


Azure at a ~$138B run rate growing 48%
Quarterly YoY growth trends below $MSFT


AWS at a ~$184B run rate growing 39%
Quarterly YoY growth trends below $AMZN


Another Anthropic S-1 myth - “They must be hiding something by not putting Q3 numbers in the S-1!”
Q3 not in this draft of the S-1 is completely normal. The quarter closed less than 30 days ago. Takes time for fully audited financials to be ready for the S-1. And for everyone saying “but didn’t they have an investor day where financials were discussed?!” Sure - and I bet those were unaudited and preliminary.
Go back and look at any tech company who went public within 30 days of the prior quarter ending. I seriously doubt they had that quarters financials in the first draft of the S-1. No one is hiding numbers, they’re just getting through audits. New listers generally take more time
Nothing is being hidden. Cerebras went public in May (Q1 quarter ended in March) without Q1 financials (most recent quarter in final S-1 was the quarter ending December). Figma final S-1 was 7/31/25. The most recent quarter, Q2, ended June 30th. Q2 wasn’t in the S-1. Again, this is normal…

Wait wait wait. The pretzel braining “Anthropic will never be profitable” crowd are now saying that the compute Anthropic gets from SpaceX is at a DISCOUNT?!?!
I mean common! Anyone paying half attention knows that the SpaceX compute comes at a massive premium. SpaceX compute may very well be the most EXPENSIVE compute
There’s honest debate, and then there’s straight up lunacy. Guess he’s got a paid newsletter to sell….

“Is this just a big circle jerk?” Jon welcomes Ed Zitron (@edzitron), host of the podcast Better Offline, to make sense of the financial house of cards propping up AI and big tech. New pod out now!
I would really strongly disagree here! And think it’s a big misconception about the S-1
Anthropic (like any startup) issues stock to raise capital early on. In most cases, that stock is preferred stock granted to institutional investor in return for capital. In other cases (again, exactly like how any other company would do it) capital is raised in convertible notes or SAFEs. These instruments don’t have a price, but instead peg a valuation (or a discount) to a future round. Discounts are the absolute norm. Company gets cash now, investor says to compensate me for giving you cash now price the security at a discount to the next round. Again, highly normal. If a convertible didn’t have a discount, there’s zero incentive for the investor to fund now. They’d just wait and fund the money when there was a known price in future. If company wants cash earlier, converts come with a discount. Doesn’t make sense to tell an investor “pay the same price now that a future investor will pay later when company is more de-risked”
Ok - so back to Anthropic. They also, like most companies, raised money in a combination of straight equity, convertible notes, SAFEs, etc. For some of the strategic investors (Amazon, Google, etc), they funded a lot of capital in convertible notes or SAFEs. Why not just straight equity? A few reasons! (This next part is more of my own speculation)
- public companies want to stay below certain ownership levels in other companies to avoid triggering “control” questions by the FTC. Notes / SAFEs don’t come with shares. They’re a promise for future shares. Large strategics can then stay under ownership thresholds in 3rd parties
- maybe Anthropic didn’t want to give governance to the strategics. Notes / SAFEs could allow the company to convert the equity into non voting stock vs voting stock
- maybe the strategics preferred converts! These securities would sit senior to preferred equity on a cap table. Anthropic was a risky early stage startup. Maybe the strategics wanted to be senior on the pref stack in case something went wrong. They’d be first to get their money back ahead of preferred investors if so
All of this to say - converts / safes are a very normal form of fundraising
Now - everyone is looking at the CURRENT p&l and saying “wait a second! Look at the value of the convertible notes / Safes! Anthropic gave away all that value at a huge discount!”
No…not true… Anthropic raised these converts / SAFEs back in time when that was about what their current equity was trading at! It just so happens that the Anthropic equity has appreciated a lot since then…Because those securities haven’t converted to equity yet, there is a mark to market change in value. It’s like saying “ah! Anthropic issued stock back in 2023 at such a discount to their current share price! So crazy! They could only issue stock back in 2023 by offering crazy discounts!” Kind of nonsense…when companies do well, share price goes up and historical prices always look cheap.
In summary - Anthropic issued converts / safes to strategics (speculative rationale listed above). They received cash in exchange for a promise of future shares. Those future shares were priced roughly where the equity was priced at the time. This then becomes a liability on the balance sheet (promise for future shares). That liability goes up in value as share price goes up (even though conversion price fixed at time). As the liability goes up, there needs to be a reduction in equity value somewhere for the balance sheet to tie. That reduction is in the form of retained earnings (which comes from income statement). So we now need an accounting entry on the income statement (ie reduction) to reflect the increase of the liability. Net income needs to be reduced by the increase of the liability.
The Anthropic net income for H1’26 was ~($80b). But just about all of that was this increase in liability of marking the convert and note to market. They didn’t lose $80b.

If you don’t want to read my long post, here’s a much more succinct version:

The effective Anthropic valuation of these 2023 and 2024 deals at the time Amazon invested is $11.2bn and $55.4bn respectively (based on current interest on the notes), which is totally in line with the fundraising history of the company. To frame this as a supplier giveaway is totally disingenuous and not borne out by the facts.
2
8
3,280
Here’s the thing - If stock were consideration for compute, GAAP would require booking the equity issued as part of the compute cost, and the filing would have to disclose non-cash consideration for the related-party purchases.
Spoiler alert - There's no such disclosure.
So many people were SO convinced that Anthropic could never be profitable that even when the numbers are right in front of them the pretzel braining continues
Great take on this today on CNBC from Roger McNamee: cnbc.com/video/2026/10/27/an…
Several of you said the same thing yesterday in the comments; i.e. $ANT's "Compute and infrastructure" cost was unrealistically low because it swapped equity for massive discounts.

Despite:
85% gross margins (H1 '26)
21% FCF margins (H1 '26)
8% FCF ex-SBC margins (H1 '26)
8% GAAP Operating Margins (Q2 '26)
$134b of cash today after raising $141b in total (and yes, this includes the converts)
There are STILL people who want to pretzel brain the "Anthropic isn't profitable" narative

How many times did we hear this leading up to the Anthropic S-1 - "Labs will never have margins!!"
Well...Serving compute per dollar of revenue fell from $0.88 to $0.15 in a year, and it fell while they were cutting price per task roughly 25–45% with each new model released
In a more classic cloud software company COGS will grow roughly in line with revenue. For Anthropic COGS grew at one-sixth the rate of revenue.

As I understand it (happy to be corrected) - The $141b raised is inclusive of the convertible notes. Those represent $11.3b of cash raised from Amazon and Google in 2023–2025. About $5b of that has since converted into preferred stock, the remaining $6.2b of principal today represents $108.6b of fair value as shown on the balance sheet as a liability (it converts at $2–5/share vs a ~$59 Series H price, so it's really ~1.8b shares, not debt).
The S-1 doesn't explicitly give a breakdown of the $141b raised, but it reconciles to include the convertible notes: $128.6b of preferred proceeds + $11.3b of convert proceeds + ~$0.6b of SAFEs/common + ~$0.7b of pre-2023 rounds = ~$141b.
