

Algorithmic trader & OSS developer. 12+ years in trading systems & exchange APIs. Building VESTROS.
Joined September 2026
- Tweets377
- Following60
- Followers49
- Likes305





I’ve been building something new.
Give VESTROS a trading indicator or strategy and it systematically explores thousands of ways its outputs could actually be used, then tries very hard to kill them.
Most ideas die.
The interesting ones end up here:
tiagosiebler.github.io/vestr…

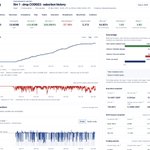
$3,450 out-of-sample on a $YM ORB algo, when the backtest expected $2,488…
over the last 6 months:
→ $10,730 net profit
→ 62.3% win rate
→ 2.48 profit factor
→ 69 trades
→ -$1,705 max drawdown
then on untouched holdout data:
→ 68.8% win rate
→ 3.12 profit factor
→ $216 average per trade
→ 16 trades
takeaway:
the holdout sample is only 16 trades, so there's still more testing to do…
but the win rate and profit factor both improved on data the optimizer never saw.

3
11
1,180

A quieter year so far for my intraday breakouts, but the equity curve is holding up quite nicely.
This is a QQQ backtest of my intraday volatility breakout, using the exact settings I share on my blog. The last few years are out of sample.
The idea is simple:
- Breakout entries at today’s open ± ATR.
- A small stop, otherwise exit at the end of the day.
- A filter to trade only days with higher potential for a larger move.

ETH daily, private tearsheet: RC1744062 is +47.25% out of sample since 1 Jan (+44.83% with fees and slippage doubled).
The catch: most of that came from one 33-day short in Jan/Feb. Since the 10 May peak it has sat in a 15.19% drawdown for 184 days, with Jul to Oct all slightly red.
Concentrated edge, or just a patient one?
tiagosiebler.github.io/vestr…

17

New release: @siebly/hyperliquid-api v1.0.3 for Node.js and TypeScript. Adds perpetual trailing stop orders for @HyperliquidX.
github.com/sieblyio/hyperliq…


this quant framework is f*cking insane
it shows why a great backtest can still be complete bullshit
the example looks strong:
in-sample Sharpe: 2.30
then you test it on unseen data:
out-of-sample Sharpe: 0.12
and the probability of finding a fake “winner” explodes as you test more strategies:
10 strategies → 4.6%
100 → 36.9%
500 → 86.5%
1,000 → 98.2%
that is the whole trap
search long enough and randomness will eventually hand you something that looks like alpha
so real quant research does the opposite:
resample
test the null
strip factors
validate out-of-sample
include real costs
the edge is not finding the best backtest
it is proving the backtest was not luck


What are the chances this crypto portfolio is reproducible after a few weeks OOS? Sharpe of almost 5 😂😂😂 short/long multi symbol, 1x leverage

2
1
39

Mostly depends on how many portfolios it beat to get picked, because the best of many gets a lift just from being chosen. And a few weeks OOS is short enough for luck to swing it either way, which is why we write down what we expect before we look.
1
11
Tiago retweeted
New release: @siebly/hyperliquid-api v1.0.3 for Node.js and TypeScript. Adds perpetual trailing stop orders for @HyperliquidX.
github.com/sieblyio/hyperliq…

ETH 4h C00297 × C00605, full directional union, out of sample since 7 Aug:
+11.84% TWR over 5 trades
10.13% max drawdown
October alone: +9.56%
Fees and slippage doubled: still +10.88%
Only 5 trades, so a small sample. The Pine is public if you want to poke at it on your own chart:
tiagosiebler.github.io/vestr…

1
29
Good to see the drawdown sitting right next to the return. With 5 trades and October carrying most of it, is the pair frozen now for the next 20, or still re-picked as data comes in?
1
11

How many of you have a small business?

Now in beta: Businesses in ChatGPT.
Claim your business, manage your information, and get insights on how people engage with you.
Eligible businesses can also build a Business Agent to answer customers’ questions and help them explore what you offer.
openai.com/index/introducing…


Updated my free open source order flow screener for crypto and forex
Website : order-flow.zadescoxp.com/
Github : github.com/zadescoxp/order-f…
Latest updates include:
1. Liquidation feed
2. Open-interest
3. Funding rate
4. Basis ( Prep vs Spot )
5. Positioning Regime
6. Big-print bubbles
7. Alerts based on events
8. Session Recoding
9. Export data
10. Resting-liquidity heatmap
11. Absorption markers
12. Venue comparing panel
13. Previous day stats
Along with major improvements and bug fixes check the latest release to know more : github.com/zadescoxp/order-f…


55% win rate. One trade a day for a year.
Chance of at least 6 losses in a row: about 69%.
More likely than not.
If your plan can't survive 6 straight losses, it's not a plan yet.
What's your rule after 3 losses?
8
10
1,531