

L/S TMT Investor, tweets are not investment advice.
New York, NY
Joined March 2016
- Tweets1.2K
- Following7.5K
- Followers5.8K
- Likes507
alphabet: six takeaways $GOOGL
the stock closed at $287.38 on tuesday, 29.7% below the $408.61 high from may. on october 29 the market cut 12.64% in one session, about $482b of value, right after the q3 print. i think it sold the cash statement and stopped reading.
1. google cloud revenue was $30.71b in q3, up 103% year over year. operating income was $11.1b. margin went from 23.7% a year ago to 36.2%.
annualized, cloud runs at roughly $123b of revenue and $44b of operating income. the whole company closed tuesday at about $3.5t.
2. cloud backlog ended q3 at $560.8b, against $513.9b in q2 and $462.3b in q1. management expects a little over 55% of it to convert inside 24 months.
anthropic owes google at least $121.3b between april 2026 and july 2033 whether it uses the capacity or not, with a true up if spending falls short. put that next to the $560.8b backlog and one customer's minimum is roughly 22% of the size of it, on take or pay terms.
3. the tpu follow on sits outside the contractual obligations table. anthropic estimates another $125b to $150b of google tpu compute for 2028 to 2031, and that range is not in the table.
i can't tell from here how much of it becomes fixed. if even half of it hardens, the same customer will have committed a second time on top of the $121.3b.
4. the bear case has receipts and they are not small. q3 operating cash flow was $42.29b against $51.36b of capex. free cash flow printed minus $9.07b, the second negative quarter in a row.
trailing twelve month free cash flow is $19.7b. capex guidance stayed at $195b to $205b for 2026, which leaves roughly $63b to $73b still to spend in q4 alone.
5. search still funds the argument while it lasts. search and other ad revenue grew 12% to $63.35b in q3.
the eps miss was uglier than the business. gaap eps came in at $2.12 against a $3.01 consensus, with an equity loss of about $8.6b in the quarter doing much of the damage.
6. street targets sit near $412, about 44% above tuesday's close. the conversion is the part with a deadline on it, a little over 55% of $560.8b inside 24 months at whatever margin cloud actually prints.
if that conversion slips a year, shareholders are left holding a $51.36b a quarter capex pace against $19.7b of trailing free cash flow.
what i'm watching is q4 capex against that $63b to $73b implied spend, and whether free cash flow stays negative while backlog keeps climbing. if cloud growth cuts in half and the 2027 capex guide rises anyway, the pitch is dead and i will say so.
source: fool.com/investing/2026/11/1…

1
341

applovin $APP: six takeaways before wednesday's print
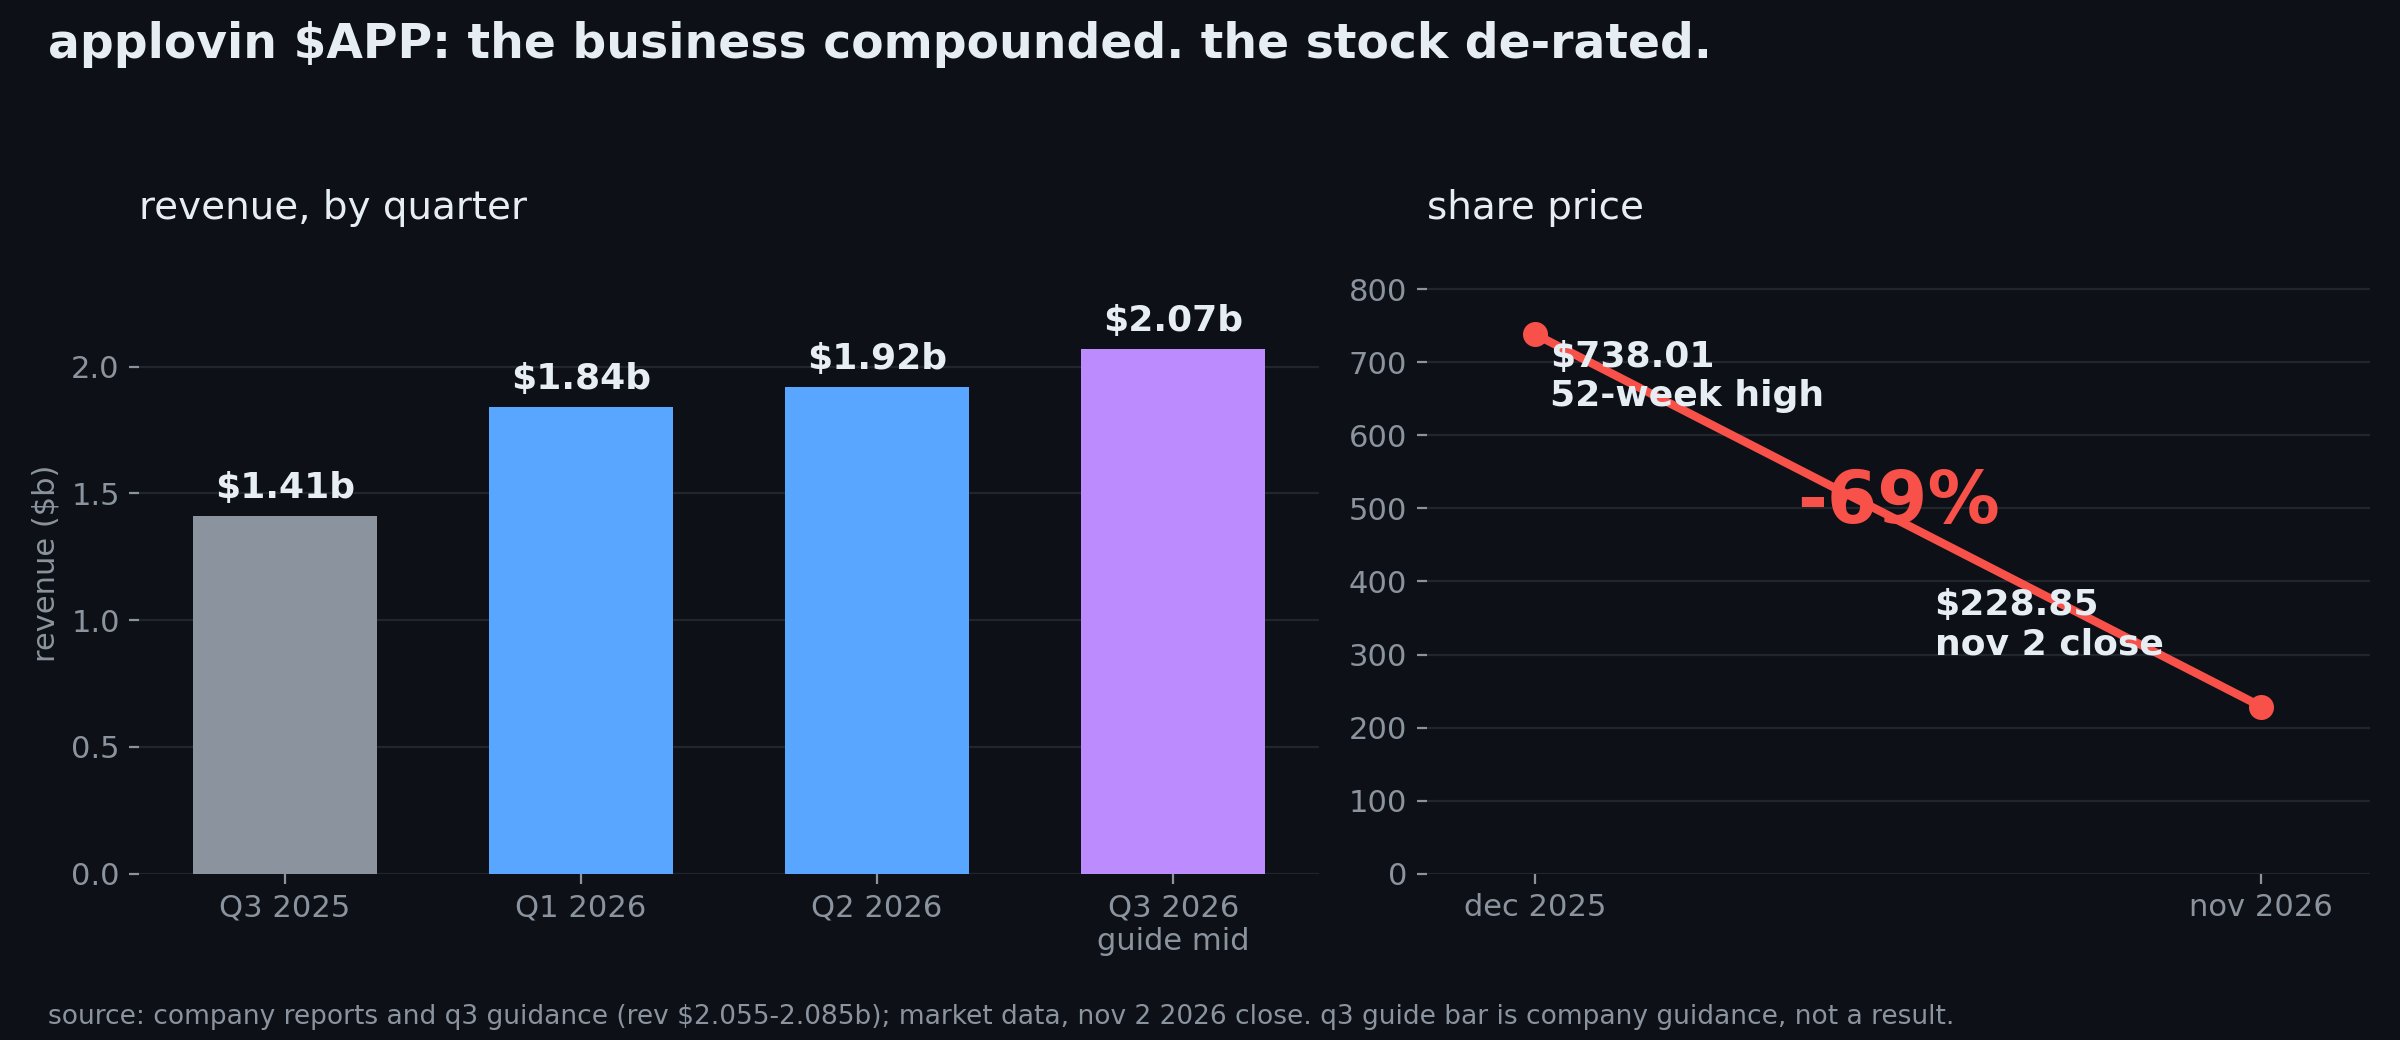
1. the stock closed monday at $228.85, down 69% from its $738.01 high, $3.66 above its 52-week low. market cap $76.6b. q2 revenue grew 53% to $1.92b at an 84% adjusted ebitda margin, with $1.27b of net income in the quarter.
three bucks above the low is one way to price a business growing like that. the de-rating ran way ahead of the income statement.
2. at $228.85 you pay 14.6x street fy26 eps of $15.67 and 11.5x fy27's $19.90, for a company guiding q3 revenue up 46 to 48%.
i'd guess the market stopped paying for growth it has to take on faith, which is fair. it is pricing a cadence problem like a demand problem.
3. q2 is the bears' whole file. revenue landed under the guide midpoint, adjusted ebitda of $1.61b missed its range, and management blamed a light quarter for model improvements. the big upgrade landed just after quarter end, they said.
one light quarter of model cadence got extrapolated into a broken engine, and i can't tell from q2 alone whether the engine actually broke.
4. tenjin's dataset puts applovin at 53% of ios ad revenue in q3, up from 44% in q2. consumer advertiser spend finished q2 28% above q4 2025 levels, the seasonal peak quarter.
tenjin is one dataset, not the whole market. share rising into the print is still a strange look for a platform supposedly losing its edge.
5. the bear case with teeth is the unit math. q2 revenue per install rose 58% while install volume fell 2%, and per-install growth had already slowed from 93% in q1.
add the securities class action, lead plaintiff deadline nov 16, alleging the company overstated how consistent the model improvements were. unproven, and it raises the cost of a second straight miss anyway.
6. management turned this into a signaling game and dealt itself the exposed hand. they named the excuse, dated it to early q3, and said the quarter started strong with the upgrade live. bluffing that is an expensive way to buy one quarter, with a class action already alleging the model story was oversold.
q3 prints wednesday after the close. consensus sits at $4.03 on $2.08b, against company guidance of $2.055b to $2.085b. options imply a double-digit move.
what i'm watching: q3 revenue against the $2.085b guide top. a second print below the midpoint kills the timing story, and management would owe a new explanation rather than a rerun of the old one. at or above the top end, shorts are short a 46 to 48% grower at 11.5x next year's street number over one quarter's model schedule.
source: marketbeat.com/earnings/repo…
s&p just moved meta to negative outlook and kept the aa- rating.
s&p puts capex at $140b this year and $225b+ in 2027. s&p's 2028 number is $252b. s&p forecasts free operating cash flow deficits of $39b in 2026 and $71b in 2027, and expects the 2028 gap to be funded entirely with debt.
meta priced $37.5b of stock offerings oct 26, including $25b of class a via forwards at $625 a share. it closed friday at $614.99, below the class a forward price, while meta told reuters it disagrees with s&p on monetization.
i can't tell from here if monetization catches up before that line gets crossed.
watch the 1.0x leverage line. s&p says it could cross as early as 2027, and that's the threshold for the aa- rating. $META
source: reuters.com/business/sp-glob…

743
anthropic's s-1 shows an $80.7b first-half loss. about $72b of it is paper.
revenue hit $16.3b in six months against $1.2b a year earlier. q2 alone did $11.6b and made $974m of operating profit.
the loss is mostly convertible notes and safes gaining value as the valuation rose. no cash left the building on that line.
the commitments are real. google $114.5b, amazon $110b and microsoft $44.9b in minimums, plus $161.2b of broadcom lease rent. that's $430.6b of firm minimums before the up-to deals, and i won't stack those into one total because the filing says the pieces aren't the same kind of promise.
the same three clouds are suppliers, investors, sales channel and competitors at once. that circle is the bet.
watch whether q2's $974m operating profit holds. if it does, the headline was accounting.
source: sec.gov/Archives/edgar/data/…

2
727
a deal sk hynix didn't operate may still pay its shareholders.
reports put a special dividend at ~16 trillion won, about $12b, funded by gains on its kioxia stake. that's ~80% of the ~20 trillion won the stake sale made in the first half, near 23,000 won a share, and about 7x last year's total dividend. seoul economic daily puts the wider package under review at 50-60 trillion won, on top of a 40 trillion won buyback-cancel already done since august. the 16 trillion won dividend is the centerpiece of that package, not on top of it.
stack it up and the year's returns would run ~90-100 trillion won. against a 931 trillion won market cap, that's ~10-11% of the company handed back if it lands. $SKHY
1. ~20 trillion won of kioxia gains, ~16 trillion of it headed back. sk hynix rode kioxia's listing as a shareholder from the 2018 bain consortium, sold down in the first half, and kept convertible bonds linked to the vehicle holding ~14% of kioxia. the windfall is balance-sheet money, not operating profit.
2. the operating print underneath is just as extreme. securities firms expect ~77 trillion won of q3 operating profit at a ~78% margin. with samsung's 107.4 trillion won prelim, the two print ~184 trillion won in one quarter. the stock still sits ~55% below its 2,987,000 won peak and ~3x next-year earnings. goldman's cut prices a 65% drop in 2027 sector earnings. those two readings pull in opposite directions.
3. 8-high hbm4 shipments, targeted for q2 2027 by both names. the ramp schedule may be the demand leg the bear case underweights.
sk hynix told the regulator on oct 26 that nothing is confirmed. it is reviewing return measures, and the board decides with wednesday's q3 print.
wednesday's print carries a board decision on the return package. if the number lands at 16 or above, the crisis multiple gets harder to defend. if it comes in light, or guidance softens 2027 pricing, tuesday's sidecar rally likely unwinds like oct 21's did.
the number to watch is the announced won figure.
source: ajupress.com/view/2026102616…

2
1,287
openai cut its own price by $150b in about three weeks.
early october, $1.4t pre, take it or leave it, shopped through morgan stanley's wealth desk. the ft says it landed with a bit of a thud.
oct 22, $1.25t pre, up to $30b, uae and coatue leading, signatures due end of next week.
same company, same month. the nasdaq had its worst day since june, meta fell 7% on its own print, spacex is lining up $40b at 8.3%. the room got colder and the ask moved with it.
the full $30b buys about 2.3% of the company. the pitch underneath: $50b annualized revenue, a $70b year-end target, to defend a number $400b above march's $852b close.
final size is still moving, so i wouldn't anchor on $30b. watch whether the signatures land.
source: aiweekly.co/alerts/openai-ne…

2
618
the memory cycle is rolling over.
cxmt preannounced rmb 53.4-54.9b of q3 net and the stock fell 6.5% anyway.
q2 net grew triple digits sequentially. q3 grew 1-4%. revenue still rose 15-20%, so the margin compressed from ~53% to ~46%.
dram contract hikes went 90-95%, then 58-63%, then 13-18%. trendforce says the 13-18% came with pc and phone buyers at their affordability limit.
the tightness held — that's the bull case, and it's real. i can't see q4 orders from here. $MU $SNDK
watch micron's print.
source: trendforce.com/news/2026/10/…

5
1,261

software was supposed to be the safe ai trade — recurring revenue, no capex.
friday the $IGV software etf fell 4.8% and finished the week down 7.4%. crowdstrike and snowflake each lost about 17% on the week. palo alto and cloudflare about 18%. twilio fell 10.6% friday, the worst in the s&p.
the cost side already priced. coreweave -25% on the week, its bonds yielding over 15%. friday the selling moved to the revenue side. software falling 17% in a week means the doubt moved from the financing to the revenue.
the number to watch is the ai revenue line on the next hyperscaler prints. if it accelerates, the revenue fear was the entry.
source: theorbitpostnews.us/wall-str…

4
555
lol coatue gave the hyperscalers a polite little 3x leverage capacity in their big ai funding chart
oracle $ORCL is already running 4.3x debt to ebitda with a bbb minus and moodys saying 5x is on the table. run the same slide at oracle's ratio and the wall of money gets to $13.7t. the constraint was never the funding math, it's how many borrowers are allowed to be oracle
fixed the chart for them 🤯
reuters.com/business/oracle-…

1
730


anthropic's equity story is a $2t ipo. kbra put the junior slice of its debt one notch below investment grade.
ft reports blackstone gets 10%+ to anchor the $18b junior tranche of anthropic's $60b "project north star" chip financing. similar borrowers pay ~7% in public bond markets. the $42b senior piece only clears with broadcom backstopping the residual value.
two trillion dollars of ambition, priced at a junk yield. i can't tell from here whether the $42b senior tranche clears the syndication.
watch that first.
source: reuters.com/business/anthrop…

3
970